 By
MONTREAL (Scrap Monster): The North American scrap market delivered a split performance during the week of September 18-24, 2026, with copper, brass/bronze, zinc and stainless steel moving higher while aluminum and most ferrous grades weakened.
Drawing on the Scrap Monster Price Index, this weekly market update examines changes in benchmark scrap values and the factors shaping buying interest, material availability and trading conditions.
The review also highlights key supply-demand developments, regional pricing, international comparisons, exchange benchmarks and broader industry trends that influenced market direction during the reporting period.
Week at a Glance
| Metal | Weekly Move | Market Read |
|---|---|---|
| Copper | ▲ Higher | All tracked grades advanced; clean grades gained 13¢-14¢/lb by region. |
| Aluminum | ▼ Mostly lower | E.C. Aluminum Wire fell 3¢/lb; several radiator, transformer and turnings grades were flat. |
| Brass/Bronze | ▲ Higher | Red and Yellow Brass advanced; Brass Radiator Ends were unchanged. |
| Lead | → Flat | Scrap Auto Batteries held steady across all three U.S. regions. |
| Zinc | ▲ Higher | New and Old Zinc Die Cast each gained 2¢/lb. |
| Steel | ▼ Mostly lower | #1 HMS, Shredded Auto Scrap and #1 Busheling each fell $5/MT; HMS 80/20 was flat. |
| Stainless Steel | ▲ Higher | 201 SS was the standout with a substantial 5% weekly gain; 304 SS Solid rose 1¢/lb. |
SCRAPMONSTER EDGE
Copper led the broad advance in North American non-ferrous scrap. Clean copper benchmark grades gained 13¢-14¢/lb across the East Coast, Midwest and West Coast, while the COMEX copper benchmark rose about 11¢/lb over the same weekly comparison. Stainless was the other standout, with 201 SS posting a substantial 5% increase.
For full daily market breakdowns, visit the Daily Scrap Metal Price Report Hub or track benchmark levels through the US Scrap Price Index.
NON-FERROUS SCRAP
Market Drivers
- Copper Supply Tightness and Stronger Benchmark Prices
Copper remains a major source of support for the non-ferrous complex, with tight mined supply and concerns over production disruptions keeping primary copper prices elevated. The market is also receiving structural support from grid investment, electrification and data-center demand. - U.S. Copper Tariff Uncertainty
Uncertainty surrounding potential U.S. tariffs on refined copper continues to influence domestic pricing, inventory positioning and import flows. Recent market commentary indicates that tariff expectations have encouraged additional copper stockpiling in the United States, tightening availability in other markets. - Aluminum Supply Constraints and High Import Costs
The U.S. aluminum market continues to contend with a gap between domestic primary production and consumption. Elevated import costs and tariff measures have strengthened the domestic price environment, potentially improving the replacement-cost basis for aluminum scrap. - Secondary Smelter and Mill Demand
Demand from secondary smelters, refiners, foundries and rolling mills continues to determine how aggressively processors compete for feedstock. Strong utilization rates can support scrap values, while softer downstream orders may encourage buyers to maintain more conservative purchasing strategies. - Electrification and Grid Investment
Longer-term demand from power-grid expansion, electrification and data-center infrastructure remains particularly important for copper and aluminum. These applications are reinforcing expectations for substantial metal requirements even as short-term industrial demand fluctuates. - Regional Price Divergence
Non-ferrous scrap markets are not moving uniformly across regions. Recent ScrapMonster data showed North American copper strengthening while Chinese copper scrap moved lower during the September 11-17 period, underscoring the influence of regional inventories, trade flows and local buying conditions.
Market read: The current environment is characterized by stronger copper fundamentals, tighter U.S. aluminum conditions, uneven regional demand and continued trade-policy uncertainty. As a result, price momentum can differ considerably by metal and grade rather than moving uniformly across the non-ferrous scrap complex.
Physical Inventory Watch — LME Stocks
Exchange inventories provide an additional physical-market signal alongside outright metal prices. As of September 24, 2026, LME warehouse stocks showed falling copper and lead inventories, a sharp one-day increase in zinc stocks, unchanged aluminum inventories and a small increase in nickel.
| Metal | LME Stocks | Daily Change | Read |
|---|---|---|---|
| Copper | 251,175 MT | ▼ 1,325 MT | Stocks declined |
| Aluminum | 241,375 MT | → 0 MT | Unchanged |
| Lead | 364,075 MT | ▼ 1,850 MT | Stocks declined |
| Zinc | 123,200 MT | ▲ 8,325 MT | Large inflow |
| Nickel | 278,898 MT | ▲ 300 MT | Slight increase |
How to read it: Inventory changes are one indicator of physical availability and should be considered alongside exchange prices, regional premiums, mill demand and scrap flows. Source: LME data compiled by Westmetall.
COPPER SCRAP PRICES
- COMEX Copper Futures closed at USD 6.7668 per pound as of September 24, 2026, approximately 11¢/lb higher than the prior week.
- According to the London Metal Exchange, the LME Copper 3-month contract closed at $14,621.00 per tonne.
MARKET HIGHLIGHTS
North America Copper Scrap Prices: Copper scrap prices extended their upward trend for another consecutive week. #1 Copper Bare Bright, #1 Copper Wire and Tubing and #2 Copper Wire and Tubing each gained 14¢/lb on the East Coast and West Coast, while the same grades rose 13¢/lb in the Midwest.
PRICE CHARTS
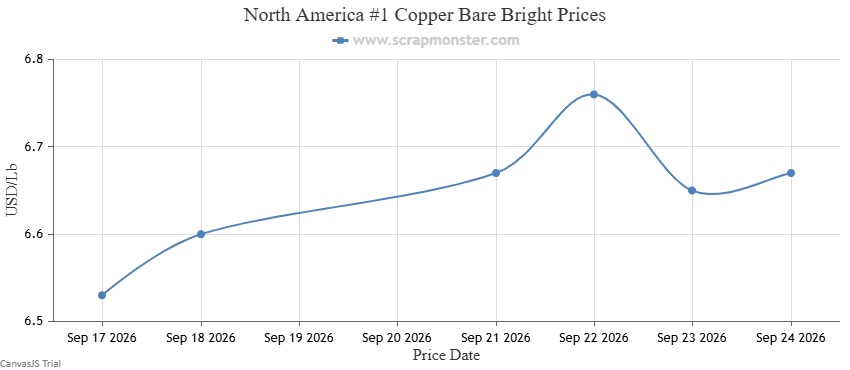
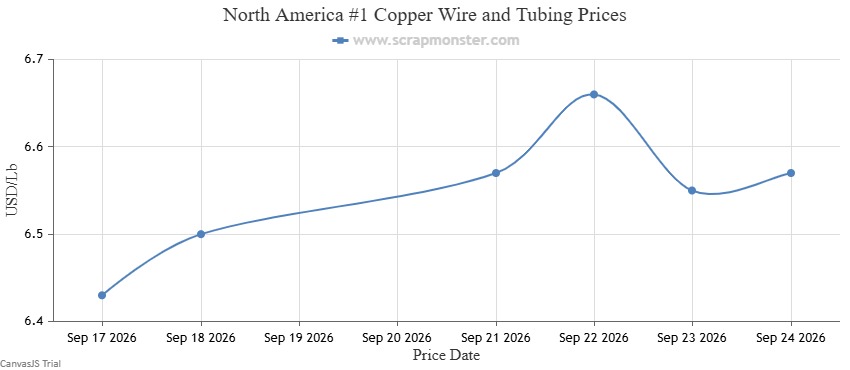
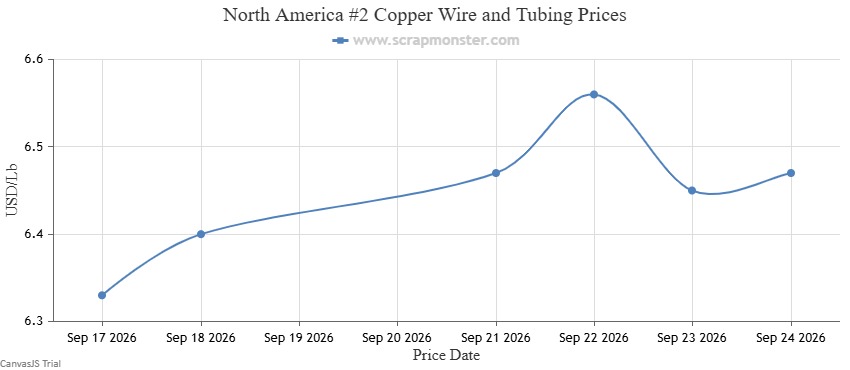
The table below outlines the week-on-week price movements for #1 Copper Bare Bright, #1 Copper Wire and Tubing and #2 Copper Wire and Tubing.
| Category | Price Change ($) |
| #1 Copper Bare Bright | 0.14 |
| #1 Copper Wire and Tubing | 0.14 |
| #2 Copper Wire and Tubing | 0.14 |
U.S. Regional Breakdown
| Region | #1 Bare Bright | #1 Wire & Tubing | #2 Wire & Tubing |
|---|---|---|---|
| East Coast | ▲ $0.14/lb | ▲ $0.14/lb | ▲ $0.14/lb |
| Midwest | ▲ $0.13/lb | ▲ $0.13/lb | ▲ $0.13/lb |
| West Coast | ▲ $0.14/lb | ▲ $0.14/lb | ▲ $0.14/lb |
International Comparison
China — Higher | India — Higher
China Copper Scrap Prices
- All major copper scrap grades recorded week-over-week price gains.
- Heater Cores and #2 Copper Wire and Tubing were among the leading weekly gainers.
India Copper Scrap Prices
- All copper scrap categories recorded a week-over-week increase.
- Copper Sheet Cutting recorded the strongest price increase, rising INR 25,000 per tonne from the previous week.
See all Copper daily reports → | Copper Price Index → | Related Copper news →
ALUMINUM SCRAP PRICES
- Aluminum Futures closed at USD 3,256.00 per metric ton as of September 24, 2026, down $41.55/MT from the previous week's close of USD 3,297.55 per metric ton.
- LME Aluminum 3-month contract closed at $3,250.00 per tonne, per the London Metal Exchange.
U.S. PHYSICAL PREMIUM WATCH
The U.S. Midwest aluminum premium was reported at approximately $1.09/lb on September 10, down from the record $1.19/lb reached in June but still elevated. The premium reflects U.S. physical-market availability, tariff and import economics and is separate from both the LME aluminum price and ScrapMonster scrap benchmarks.
MARKET HIGHLIGHTS
North America Aluminum Scrap Prices: Aluminum scrap prices edged lower during the week. E.C. Aluminum Wire fell 3¢/lb, while 6063 Extrusions, Old Cast and UBC each slipped 1¢/lb.
PRICE CHARTS
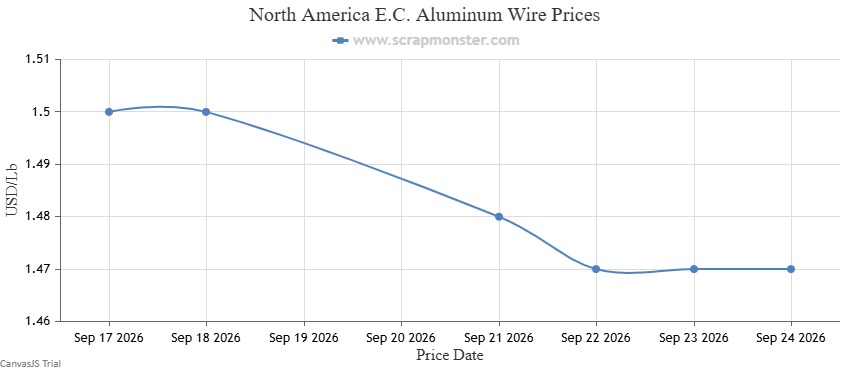
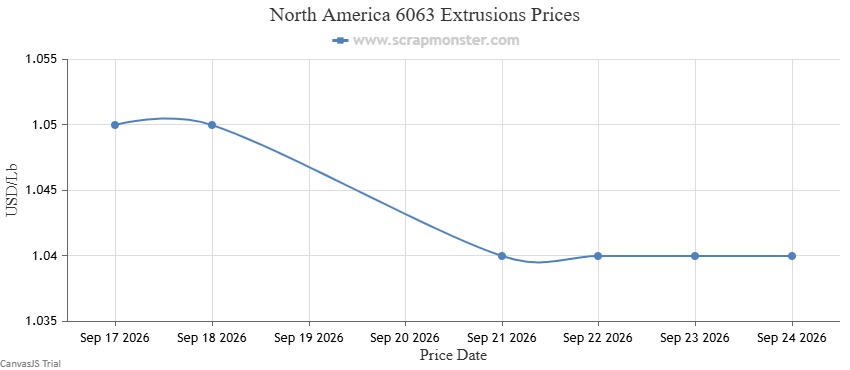
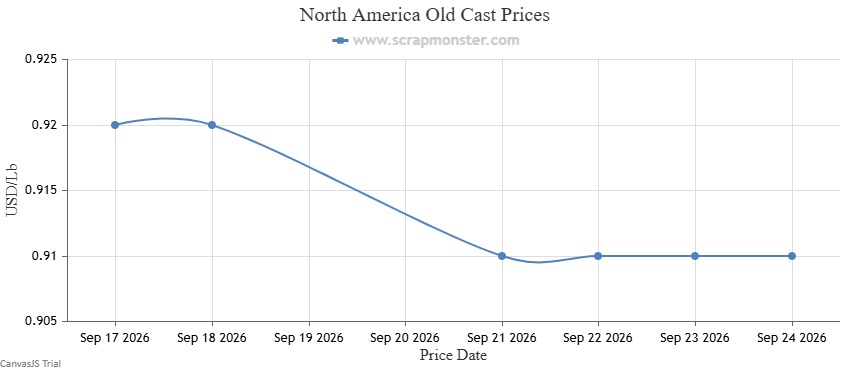
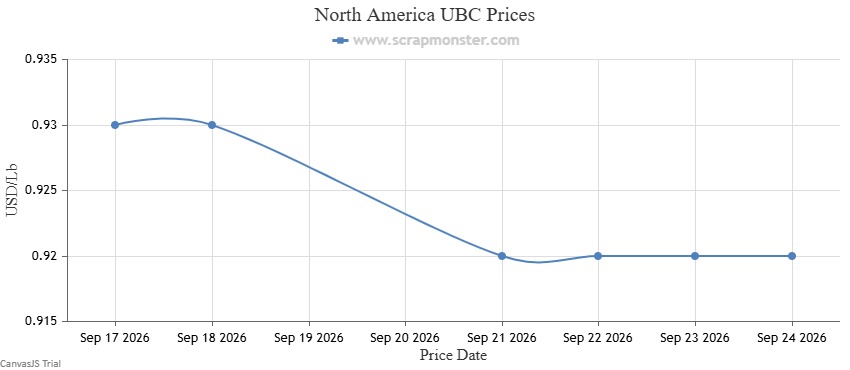
The table below provides weekly price fluctuations in E.C. Aluminum Wire, 6063 Extrusions, Old Cast and UBC.
| Category | Price Change ($) |
| E.C. Aluminum Wire | 0.03 |
| 6063 Extrusions | 0.01 |
| Old Cast | 0.01 |
| UBC | 0.01 |
U.S. Regional Breakdown
| Region | E.C. Aluminum Wire | 6063 Extrusions | Old Cast | UBC |
|---|---|---|---|---|
| East Coast | ▼ $0.03/lb | ▼ $0.01/lb | ▼ $0.01/lb | ▼ $0.01/lb |
| Midwest | ▼ $0.03/lb | ▼ $0.01/lb | ▼ $0.01/lb | ▼ $0.01/lb |
| West Coast | ▼ $0.03/lb | ▼ $0.01/lb | ▼ $0.01/lb | ▼ $0.01/lb |
International Comparison
China Aluminum Scrap Prices
- All aluminum scrap categories held steady from the previous week's prices.
India Aluminum Scrap Prices
- All aluminum scrap categories inched lower on the Scrap Monster Price Index.
- Aluminum utensil scrap prices were down by INR 3,000 per ton.
See all Aluminum daily reports → | Aluminum Price Index → | Related Aluminum news →
BRASS/BRONZE SCRAP PRICES
MARKET HIGHLIGHTS
North America Brass/Bronze Scrap Prices: Brass and bronze scrap maintained their upward momentum during the week. Red Brass and Yellow Brass each gained 4¢/lb on the North American benchmark, while Brass Radiator Ends were unchanged.
PRICE CHARTS
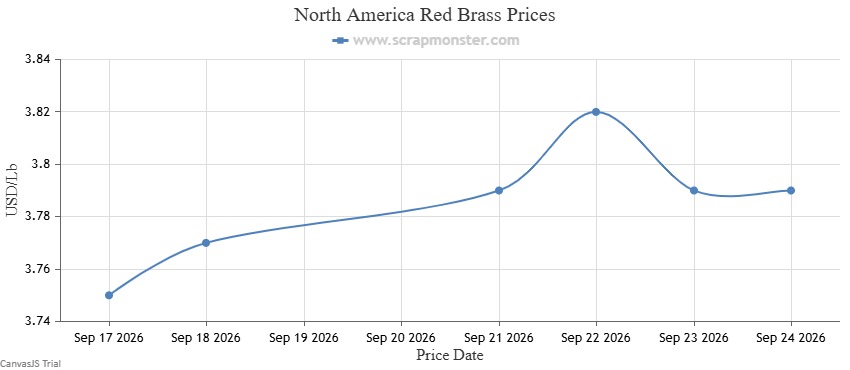
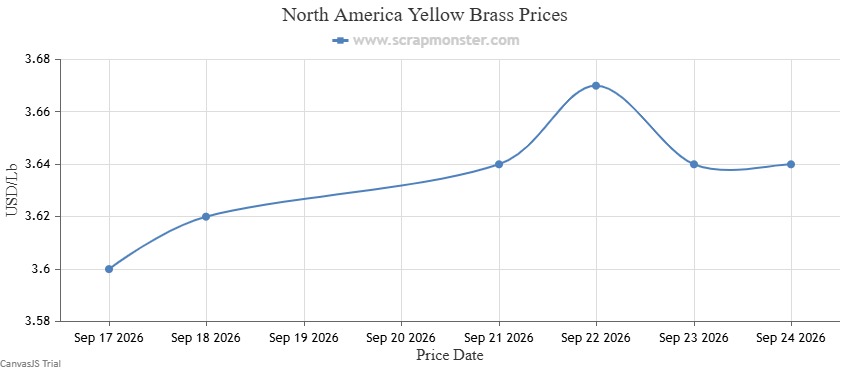
The table below provides weekly price fluctuations in Yellow Brass and Red Brass.
| Category | Price Change ($) |
| Red Brass | 0.04 |
| Yellow Brass | 0.04 |
U.S. Regional Breakdown
| Region | Red Brass | Yellow Brass |
|---|---|---|
| East Coast | ▲ Higher | ▲ Higher |
| Midwest | ▲ Higher | ▲ Higher |
| West Coast | ▲ $0.04/lb | ▲ Higher |
International Comparison
China — Higher | India — Higher
China Brass/Bronze Scrap Prices
- All brass/bronze scrap categories recorded a slight jump.
- Red Brass and Yellow Brass prices each increased by CNY 500 per metric ton.
India Brass/Bronze Scrap Prices
- All brass/bronze scrap categories edged higher.
- Brass Cuttings recorded the largest weekly gain, rising INR 5,000 per tonne.
See all Brass/Bronze daily reports → | Brass/Bronze Price Index → | Related Brass/Bronze news →
LEAD SCRAP PRICES
- Lead benchmark prices increased by $26.23 per ton over the prior week to close at USD 1,940.43 per ton as of September 24, 2026.
- The closing price of the LME Lead 3-month contract was $1,934.00 per metric tonne, per London Metal Exchange data.
MARKET HIGHLIGHTS
North America Lead Scrap Prices: The lead scrap market remained flat throughout the week, reflecting balanced supply and demand conditions. Scrap Auto Battery prices likewise showed no movement, ending the week unchanged from the previous week's levels.
PRICE CHART
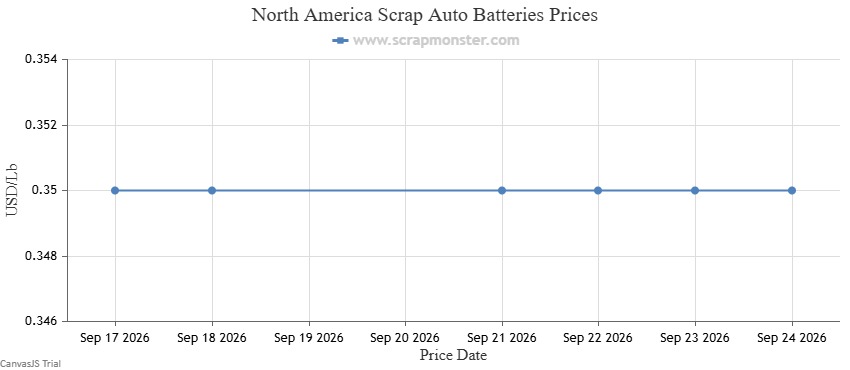
The table below provides weekly price fluctuations in Scrap Auto Batteries.
| Category | Price Change ($) |
| Scrap Auto Batteries | 0 |
U.S. Regional Breakdown
| Region | Scrap Auto Batteries |
|---|---|
| East Coast | → Flat |
| Midwest | → Flat |
| West Coast | → Flat |
International Comparison
China — Higher | India — Higher
China Lead Scrap Prices
- Soft Lead and #2 Lead Scrap prices both recorded modest weekly increases.
- Auto Battery prices edged higher from the prior week.
India Lead Scrap Prices
- The prices of all lead scrap categories in the region increased over the previous week.
See all Lead daily reports → | Lead Price Index → | Related Lead news →
ZINC SCRAP PRICES
- Zinc benchmark prices closed at USD 3,976.85 per metric ton as of September 24, 2026, up $88.15/MT from the prior week.
- The LME Zinc 3-month contract closed at $3,955.00 per tonne.
MARKET HIGHLIGHTS
North America Zinc Scrap Prices: Zinc scrap prices edged higher versus the previous week. New Zinc Die Cast and Old Zinc Die Cast each gained 2¢/lb.
PRICE CHARTS
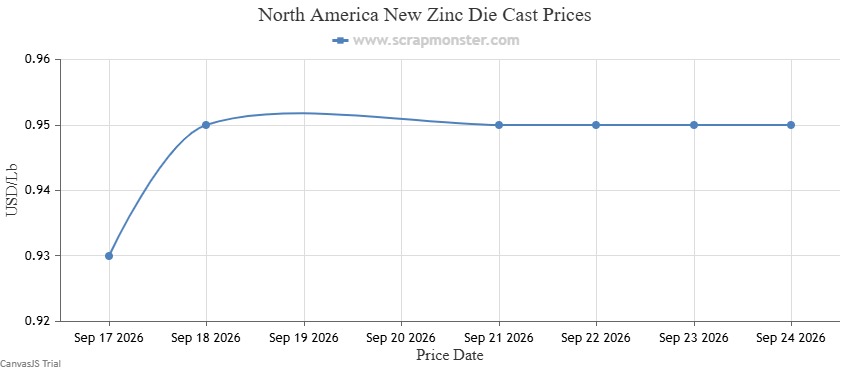
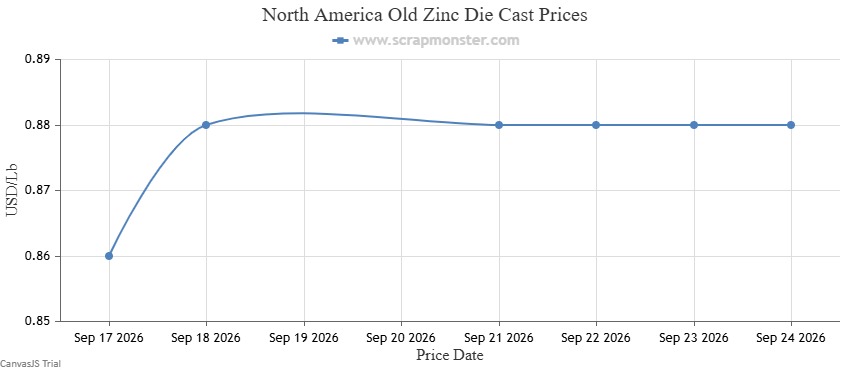
The table below provides weekly price fluctuations in New Zinc Die Cast and Old Zinc Die Cast.
| Category | Price Change ($) |
| New Zinc Die Cast | 0.02 |
| Old Zinc Die Cast | 0.02 |
U.S. Regional Breakdown
| Region | New Zinc Die Cast | Old Zinc Die Cast |
|---|---|---|
| East Coast | ▲ Higher | ▲ Higher |
| Midwest | ▲ Higher | ▲ Higher |
| West Coast | ▲ Higher | ▲ Higher |
International Comparison
China — Higher | India — Higher
China Zinc Scrap Prices
- Shred Zinc Scrap prices increased by CNY 350 per metric ton during the week ended September 24, 2026.
India Zinc Scrap Prices
- Tin Slab prices held steady week over week.
- Zinc Slab prices increased over the previous week.
See all Zinc daily reports → | Zinc Price Index → | Related Zinc news →
FERROUS SCRAP
Market Drivers
- EAF Mill Demand Remains a Key Price Driver
Electric arc furnace (EAF) steelmakers remain the primary source of domestic ferrous scrap demand in the U.S. However, recent market commentary suggests that the expansion of EAF capacity has not yet translated into a proportionate increase in scrap prices. - Scrap Supply Remains Relatively Balanced
Scrap availability and mill inventories are currently providing little evidence of a major supply imbalance. Fastmarkets' September survey placed U.S. scrap inventories close to normal levels, limiting pressure for either aggressive buying or substantial price concessions. - Finished Steel Prices and Mill Margins
The relationship between finished steel prices and scrap costs remains central to mill purchasing decisions. Stronger steel pricing can improve margins and provide mills with greater room to absorb higher scrap costs, although the recent market has shown that rising steel prices do not automatically translate into equivalent scrap gains. - Export Demand and Global Competition
U.S. ferrous scrap exporters continue to compete with domestic mills for available material. Conditions in Turkey, Asia and other major buying regions can therefore influence coastal U.S. prices, with recent September market reports showing relatively stable export pricing and continued uncertainty among exporters. - Trade Policy and Import Competition
U.S. steel tariffs and changing trade flows continue to reshape the domestic steel market. Higher import barriers can support domestic steel pricing and production, but they can also alter export economics and the competitive position of U.S. scrap in international markets. - Construction and Manufacturing Activity
Demand for long steel products, flat steel and other finished products provides an important downstream signal for scrap consumption. Any improvement or deterioration in construction, automotive and manufacturing activity can feed through to mill production schedules and subsequently alter scrap purchasing requirements.
Market read: The current ferrous scrap market is being shaped by a combination of steady EAF consumption, balanced inventories, finished-steel pricing, export conditions and disciplined mill purchasing. The latest U.S. market assessments point to limited directional momentum rather than a broad-based price move, with regional and grade-level differences likely to remain important.
STEEL SCRAP PRICES
MARKET HIGHLIGHTS
The closing prices of various LME 2-month steel contracts on the London Metal Exchange as of September 24, 2026, are provided below:
Steel Scrap CFR Turkey (Platts) — $402.00 per tonne
Steel Rebar FOB Turkey (Platts) — $620.00 per tonne
Steel Scrap CFR India (Platts) — $408.30 per tonne
North America Steel Scrap Prices: Steel scrap prices recorded a generally weak trend during the week. #1 HMS, Shredded Auto Scrap and #1 Busheling each fell $5/MT, while HMS 80/20 remained flat.
According to the American Iron and Steel Institute (AISI), U.S. raw steel production totaled 1.785 million net tons during the week ended September 19, 2026 — ↑0.60% year-on-year but ↓6.10% week-on-week. The capability utilization rate stood at 77.90%, versus 82.30% in the week ending September 12, 2026.
Year-to-date context: Adjusted U.S. raw steel production through September 19 totaled 68.322 million net tons, up ↑5.3% from 63.093 million net tons during the same period in 2025. Year-to-date capability utilization averaged 79.0%, compared with 77.2% a year earlier. The broader YTD increase helps distinguish the latest weekly decline from the underlying 2026 production trend.
Region-wise production: Northeast — 128,000 NT; Great Lakes — 528,000 NT; Midwest — 275,000 NT; Southern — 818,000 NT; Western — 36,000 NT.
PRICE CHARTS
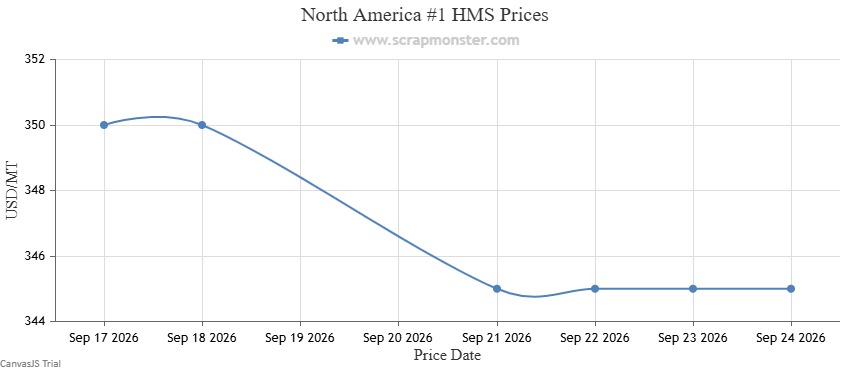
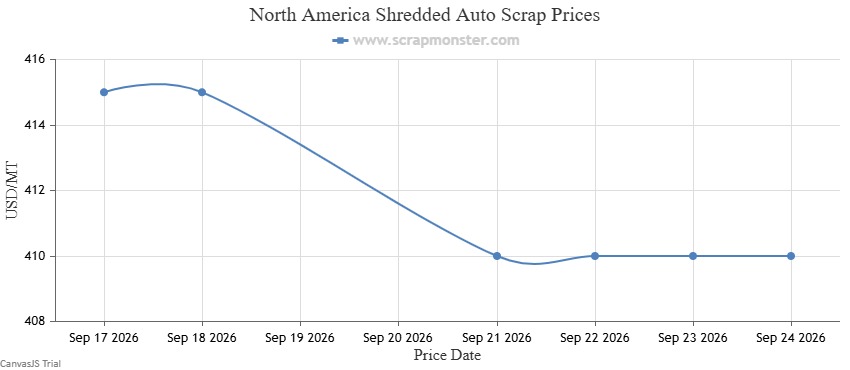
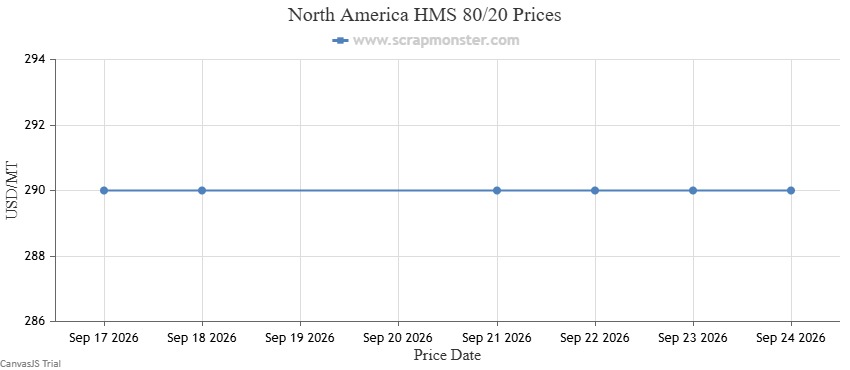
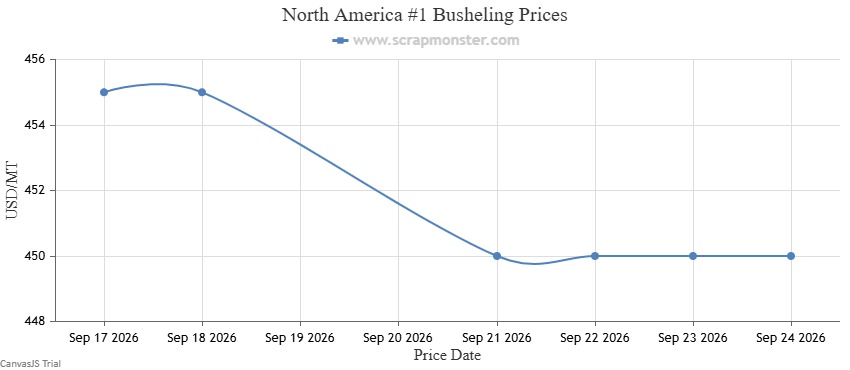
The table below provides weekly price variations in #1 HMS, Shredded Auto Scrap, HMS 80/20 and #1 Busheling.
| Category | Price Change ($) |
| #1 HMS | 5 |
| Shredded Auto Scrap | 5 |
| HMS 80/20 | 0 |
| #1 Busheling | 5 |
U.S. Regional Breakdown
| Region | #1 HMS | Shredded Auto | #1 Busheling | HMS 80/20 |
|---|---|---|---|---|
| East Coast | ▼ $5/MT | ▼ $5/MT | ▼ $5/MT | → Flat |
| Midwest | ▼ $5/MT | ▼ $5/MT | ▼ $5/MT | → Flat |
| West Coast | ▼ $5/MT | ▼ $5/MT | ▼ $5/MT | → Flat |
International Comparison
China — Flat
China Steel Scrap Prices
- All steel scrap categories held steady.
- #1 HMS and Cast Iron Scrap prices remained flat versus the previous week.
See all Steel daily reports → | Steel Price Index → | Related Steel news →
STAINLESS STEEL SCRAP PRICES
- LME Nickel 3-month contract closed at $16,475 per tonne on September 24, up $125/MT from $16,350 per tonne on September 17.
MARKET HIGHLIGHTS
North America Stainless Steel Scrap Prices: The stainless steel scrap market moved higher during the week. 201 SS was the standout with a substantial ↑5.0% weekly gain, while 304 SS Solid rose 1¢/lb.
PRICE CHART
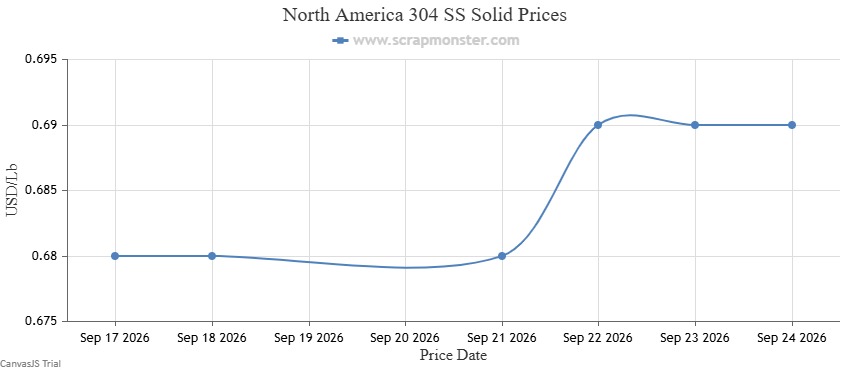
The table below provides weekly price fluctuations in 304 SS Solid scrap.
| Category | Price Change ($) |
| 304 SS Solid | 0.01 |
U.S. Regional Breakdown
| Region | 304 SS Solid |
|---|---|
| East Coast | ▲ $0.01/lb |
| Midwest | ▲ $0.01/lb |
| West Coast | ▲ $0.01/lb |
International Comparison
China — Higher
China Stainless Steel Scrap Prices
- All scrap categories, except 201 SS, posted a jump in prices during the week ended September 24, 2026.
- 304 SS Turning was the top gainer among the tracked Chinese stainless grades.
See all Stainless Steel daily reports → | Stainless Steel Price Index → | Related Stainless Steel news →
Weekly Market Drivers
- U.S. Steel Mill Production — AISI: U.S. Steel Output Rises 0.6% Y-on-Y in Mid-September
- Steel Commitment — USW welcomes Canadian steel commitment for North Coast Transmission Line
- Trade Talks — Mexico-US Trade Talks Delayed as Tariff Relief Tops Agenda
- Contract Renewal/Negotiations — USW: Contract Talks with U.S. Steel "Extremely Disappointing"
- Steel Output — Italy's steel production fell by 3.5% y/y in August
- Earnings Outlook — Steel Dynamics Sees Q3 2026 Earnings Surge Amid Strong Steel Demand
- Carbon Emissions — Lower-carbon steel and permanent storage CCS expands across the Gulf Coast
- Metal Recycling — BIR: EU Waste Rules Could Disrupt Global Metal Recycling
- Steel Investment — U.S. Steel Commences $475 Million Q&T Project at Alabama Tubular Plant
Global Scrap Comparison — U.S. vs. China/India
| Metal | U.S. | China | India |
|---|---|---|---|
| Copper | ▲ Higher — clean grades +13¢ to +14¢/lb by region | ▲ Higher | ▲ Higher — Copper Sheet Cutting +INR 25,000/tonne |
| Aluminum | ▼ Lower — E.C. Wire -3¢/lb | → Flat | ▼ Lower — utensil scrap -INR 3,000/ton |
| Brass/Bronze | ▲ Higher | ▲ Higher — Red/Yellow Brass +CNY 500/MT | ▲ Higher — Brass Cuttings +INR 5,000/tonne |
| Lead | → Flat | ▲ Higher | ▲ Higher |
| Zinc | ▲ Higher — die cast grades +2¢/lb | ▲ Higher — Shred Zinc +CNY 350/MT | ▲ Higher |
| Steel | ▼ Lower — selected grades -$5/MT | → Flat | — |
| Stainless Steel | ▲ Higher — 304 SS Solid +1¢/lb; 201 SS led the market | ▲ Higher | — |
POLICY CONTEXT
U.S. Section 232 measures continue to influence landed costs, inventory positioning and metal trade flows, although current tariff treatment varies by product and origin. Copper scrap itself was excluded from the 2025 copper Section 232 tariff, while the policy framework established a domestic-sales requirement for a share of high-quality U.S. copper scrap. A separate phased tariff on refined copper for 2027 remained subject to a later presidential determination following a Commerce review. For steel and aluminum, 2026 tariff changes also introduced product- and origin-specific treatment, so the market impact cannot be reduced to a single uniform tariff rate.
SCRAPMONSTER MARKET DIVERGENCE
Physical scrap did not move in lockstep with primary benchmarks. Copper scrap strengthened more sharply than the exchange move in cents per pound, aluminum scrap weakened alongside a lower primary benchmark, zinc scrap tracked a firmer zinc market, and scrap auto batteries remained flat even as the lead benchmark rose.
| Market | Scrap Move | Primary Benchmark | Read |
|---|---|---|---|
| Copper | Clean grades +13¢ to +14¢/lb by region | COMEX approximately +11¢/lb | Scrap outpaced the weekly futures move |
| Aluminum | E.C. Wire -3¢/lb; selected grades -1¢/lb | Benchmark -$41.55/MT | Both moved lower |
| Zinc | Die Cast grades +2¢/lb | Benchmark +$88.15/MT | Both moved higher |
| Lead | Scrap Auto Batteries flat | Benchmark +$26.23/ton | Scrap lagged the primary market |
Why it matters: Exchange prices and scrap values do not move one-for-one. Divergence can reflect grade availability, freight, recovery economics, local inventories and competition for feedstock.
Expert Quote
“Despite a surge in steel prices and an increased melt rate, the price of ferrous scrap has only marginally improved.” — Stephen Miller, Steel Market Update, September 24, 2026.
Market Outlook
- U.S. Scrap Prices Likely to Remain Relatively Range-Bound
The latest U.S. market assessment points to a broadly sideways near-term outlook, with limited momentum for a major price move. Fastmarkets' September survey put its Trend Indicator at 49.5, close to the level associated with flat pricing. - EAF Capacity Will Continue to Support Baseline Demand
The continued expansion of electric arc furnace (EAF) steelmaking provides a structural source of scrap demand. However, current market commentary indicates that increased EAF capacity has not yet produced a proportionate increase in scrap prices. - Mill Buying Is Expected to Remain Disciplined
Steelmakers are likely to maintain cautious purchasing strategies while assessing finished-steel demand and operating economics. With inventories reported near normal levels, mills have less immediate need to aggressively rebuild scrap stocks. - Export Markets Remain an Important Swing Factor
International buying, particularly from major scrap-importing markets, will continue to influence U.S. exporters and coastal scrap values. Recent strength in Turkish domestic scrap purchasing suggests that overseas demand can provide an additional outlet for U.S. material, although trade flows remain sensitive to steel economics. - Scrap Supply Is Likely to Stay Closely Balanced With Demand
Normal inventory conditions suggest that neither an acute shortage nor a significant oversupply is currently dominating the market. This balance could keep prices relatively stable unless collection volumes or mill consumption change materially. - Trade Policy Will Continue to Shape Steel and Scrap Flows
U.S. steel trade measures have altered import economics and domestic market dynamics. Changes in tariffs and resulting shifts in steel trade flows could influence domestic production levels and, consequently, the amount of scrap required by U.S. mills.
BOTTOM LINE
Copper remains the strongest part of the weekly North American scrap tape, while aluminum and ferrous scrap were softer. Brass/bronze and zinc also moved higher, lead stayed flat, and stainless strengthened, led by 201 SS. For the coming week, mill buying discipline, export conditions, exchange inventories and the next round of manufacturing and employment data remain the main variables to watch.
WATCHLIST FOR UPCOMING WEEK
U.S.
- Tue: S&P/Case-Shiller Home Price Index (July), CB Consumer Confidence (September)
- Wed: ADP Employment Report (September), Personal Income & Spending (August)
- Thu: Weekly Jobless Claims
- Fri: ISM Manufacturing PMI (September)
Europe (EU & UK)
- Tue: Eurozone Economic Sentiment (September), Eurozone Consumer Confidence (September - Final)
- Wed: Germany Unemployment Rate (September), Eurozone Core & Headline CPI Flash Estimate (September)
Asia & Oceania
- Mon: India-IIP (August), Singapore-Industrial Production (August)
- Tue: Australia-CPI (August) & RBA Monetary Policy Minutes, Japan-Industrial Production (August - Preliminary) & Retail Sales (August), China-NBS Manufacturing PMI (September) and South Korea-Industrial Production (August)
Daily Reports | Scrap Monster Price Index | US Scrap Metal Prices
DATA & METHODOLOGY
This report covers the weekly comparison period of September 18-24, 2026, unless otherwise stated. ScrapMonster Price Index movements are benchmark buying-price trends and should not be interpreted as guaranteed local yard or processor quotes.
- Actual transaction and yard prices can vary by grade, preparation, recovery, volume, location, freight and buyer.
- COMEX/LME and other exchange values are included as reference benchmarks; they are not direct scrap valuations and do not move one-for-one with physical scrap.
- ScrapMonster reports price moves primarily in ¢/lb, $/lb, $/MT, CNY/MT or INR/tonne. Percentage changes are reserved for unusually large moves where the percentage itself adds meaningful market context.
- International comparisons reflect the relevant ScrapMonster regional benchmark series and may cover different grade mixes from U.S. comparisons.
- LME inventory figures in the Physical Inventory Watch are as of September 24, 2026.
- The U.S. Midwest aluminum premium is included as physical-market context and is separate from both the LME price and ScrapMonster scrap benchmarks.
Reference sources used for contextual benchmarks include ScrapMonster market data, London Metal Exchange data, American Iron and Steel Institute production data and reported U.S. aluminum physical-premium assessments.
Related Resources: Copper Scrap Prices | Aluminum Scrap Prices | Steel Scrap Prices | Brass Scrap Prices | Scrap Yard Directory | Company Directory | Daily Market Report
Full pricing details, yard finder, market analysis and live price charts are available at ScrapMonster.com. Trusted by 100,000+ recycling professionals. Sign up for daily alerts—your competitive edge starts here.