 By
North American Scrap Prices Diverge as Aluminum Falls and Steel Holds
North American scrap markets produced a mixed week from October 2 through October 8, with aluminum and zinc mostly lower, copper split by region, brass and lead unchanged, and ferrous benchmarks largely stable apart from gains in selected prime grades.
By Carolina Curiel
Published October 9, 2026
Reporting period: October 2-8, 2026
Key Points
- Copper: Regional markets diverged. Key East and West Coast clean grades gained ↑2¢/lb, while comparable Midwest grades fell about ↓4¢/lb. Cu Yokes and Heater Cores were among the strongest percentage gainers.
- Aluminum: Most tracked grades declined. E.C. Aluminum Wire posted the largest listed drop at ↓3¢/lb, or ↓2.13%, while Breakage 50% Recovery gained ↑1.79%.
- Brass/Bronze and Lead: North American benchmarks remained unchanged.
- Zinc: New and Old Zinc Die Cast each fell ↓1¢/lb.
- Steel: Most benchmarks held steady, while #1 Bundle and #1 Busheling gained ↑$10/MT.
- Stainless Steel: 304 SS Solid declined ↓1¢/lb, or ↓1.47%, while 201 SS held steady.
MONTREAL (Scrap Monster): North American scrap markets moved in different directions during the week ended October 8, 2026, with weakness concentrated in aluminum, zinc and selected stainless steel grades while most ferrous benchmarks remained stable.
The week also showed a pronounced regional split in copper. East and West Coast clean copper benchmarks moved higher, while comparable Midwest grades declined.
These are ScrapMonster broker buying benchmark movements. Local yard quotations can vary by grade, location, volume and market conditions.
Copper Splits by Region as Futures Edge Higher
COMEX copper futures finished October 8 at US$6.5658 per pound, approximately ↑0.43% above the prior week's level. The LME three-month copper contract closed at US$14,309 per tonne.
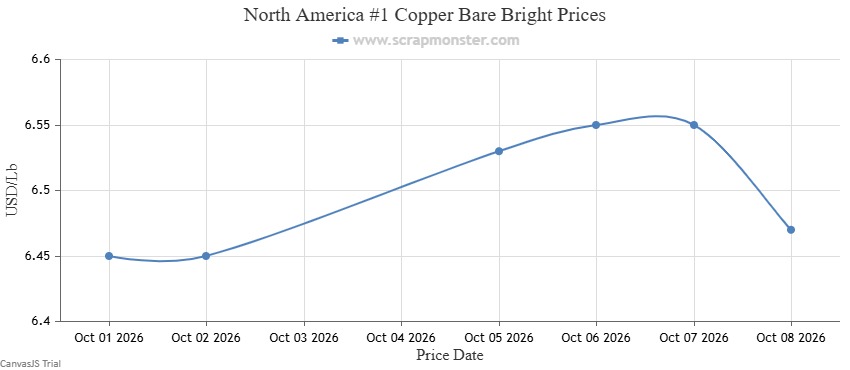
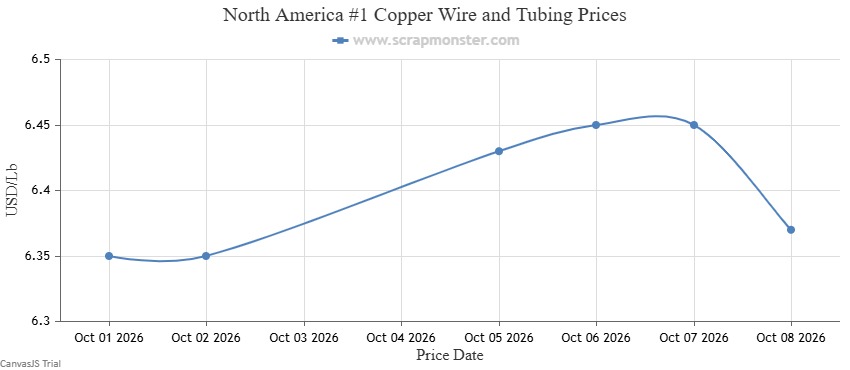
On the ScrapMonster Price Index, East Coast #1 Copper Bare Bright and #1 Copper Wire & Tubing each gained ↑2¢/lb, or ↑0.31%. #2 Copper Wire & Tubing also rose ↑2¢/lb, or ↑0.32%.
Across the broader copper list, Cu Yokes posted one of the strongest weekly percentage gains at ↑0.68%, while Heater Cores advanced ↑0.37%.
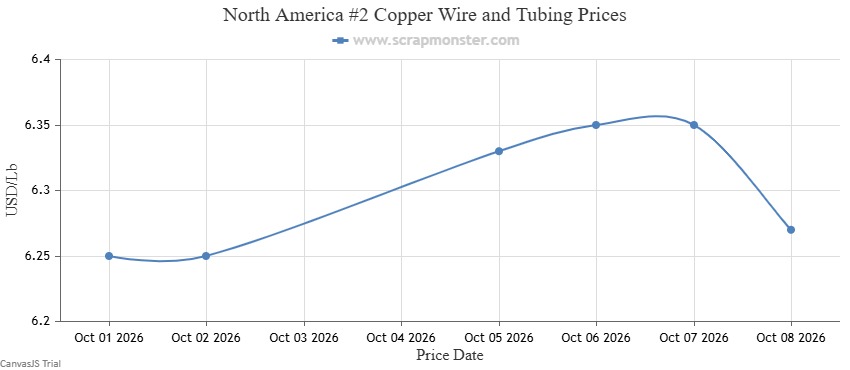
| Copper Grade | Weekly Change | % Change |
|---|---|---|
| #1 Copper Bare Bright | ↑2¢/lb | ↑0.31% |
| #1 Copper Wire & Tubing | ↑2¢/lb | ↑0.31% |
| #2 Copper Wire & Tubing | ↑2¢/lb | ↑0.32% |
Regional Copper Movements
East Coast: #1 Copper Bare Bright and #1 Copper Wire & Tubing each gained ↑2¢/lb, while #2 Copper Wire & Tubing also advanced ↑2¢/lb.
Midwest: #1 Copper Bare Bright fell ↓4¢/lb, or ↓0.62%. #1 Copper Wire & Tubing declined ↓4¢/lb, or ↓0.63%, while #2 Copper Wire & Tubing fell ↓0.64%.
West Coast: #1 Copper Bare Bright and #1 Copper Wire & Tubing each gained ↑2¢/lb, while #2 Copper Wire & Tubing advanced approximately ↑0.31%.
International comparison: China ↑0.42% | India ↑1.32%
Aluminum Weakens Across Key Grades
Aluminum was one of the clearest weak spots in the North American market. CME/COMEX aluminum futures closed October 8 at US$3,041.50 per metric ton, ↓2.52% from the prior week's US$3,120.15. The LME three-month contract closed at US$3,050.50 per tonne.
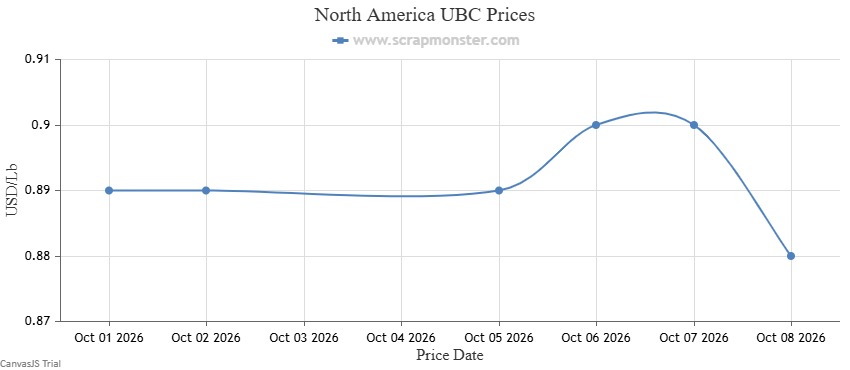
E.C. Aluminum Wire fell ↓3¢/lb, or ↓2.13%. 6063 Extrusions declined ↓1¢/lb, or ↓0.99%; Old Cast lost ↓1¢/lb, or ↓1.14%; and UBC fell ↓1¢/lb, or ↓1.12%.
Not every grade moved lower. Aluminum Radiators, Aluminum Radiators/Fe, Al/Cu Radiators, Al/Cu Radiators/Fe and Aluminum Transformers remained unchanged during the week. Breakage 50% Recovery was the principal listed gainer, rising ↑1.79%.
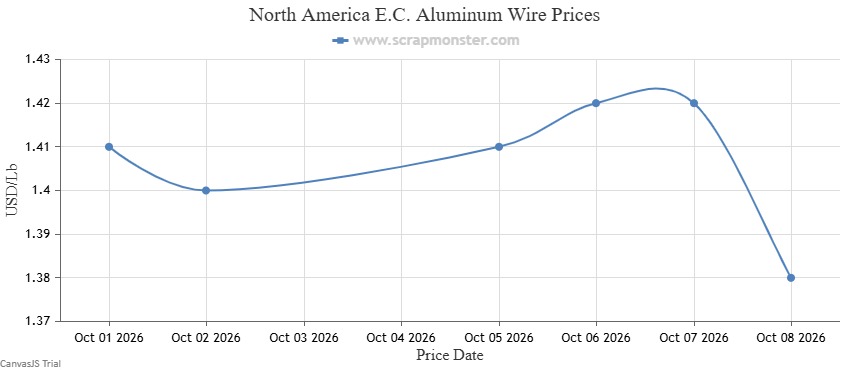
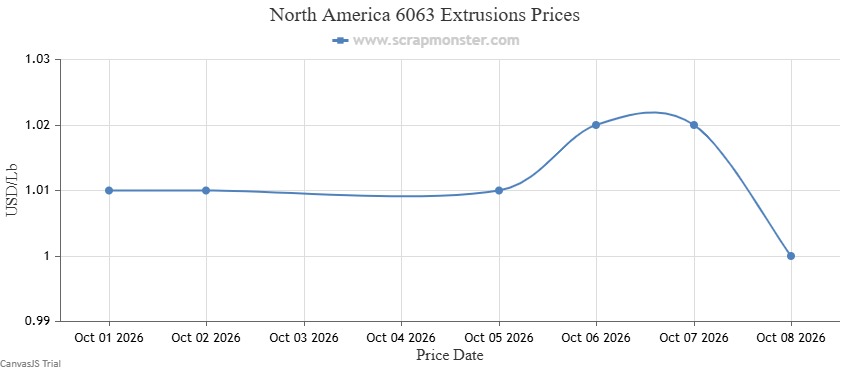
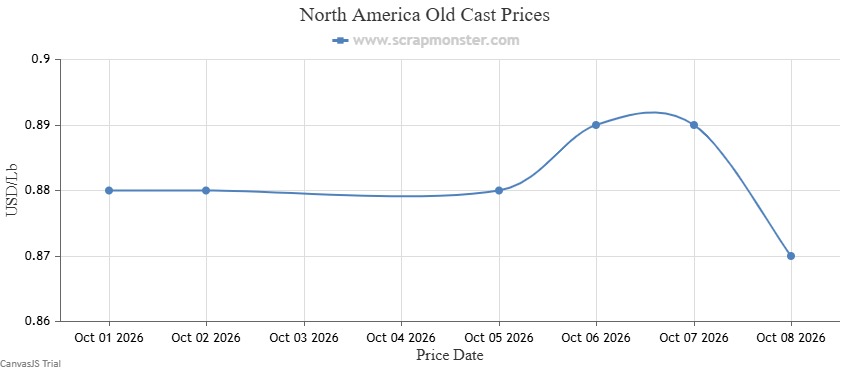
| Aluminum Grade | Weekly Change | % Change |
|---|---|---|
| E.C. Aluminum Wire | ↓3¢/lb | ↓2.13% |
| 6063 Extrusions | ↓1¢/lb | ↓0.99% |
| Old Cast | ↓1¢/lb | ↓1.14% |
| UBC | ↓1¢/lb | ↓1.12% |
International comparison: China ↓1.87% | India → Flat
Brass and Bronze Hold Steady
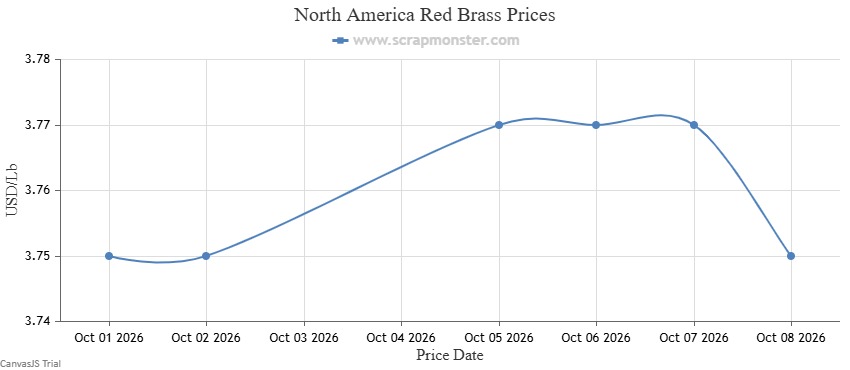
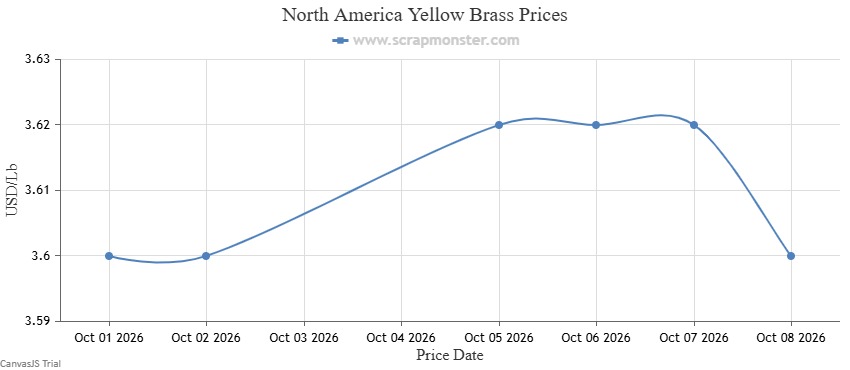
North American brass and bronze benchmarks recorded no weekly change. Red Brass and Yellow Brass remained flat across the principal regional comparisons.
| Brass/Bronze Grade | Weekly Change | % Change |
|---|---|---|
| Red Brass | → 0 | → Flat |
| Yellow Brass | → 0 | → Flat |
International comparison: China ↑0.24% | India ↑0.83%
Lead Scrap Remains Flat
COMEX lead futures were nearly unchanged during the week, slipping a nominal US$0.03 per ton, or ↓0.001%, to close October 8 at US$1,863.55 per ton.
The LME three-month lead contract closed at US$1,860 per metric tonne.
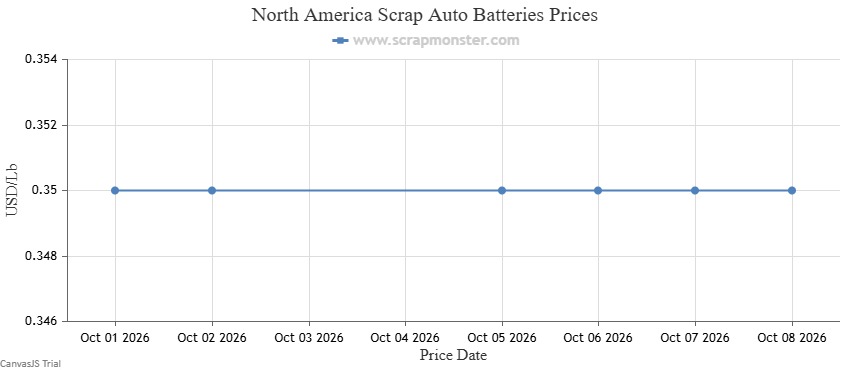
North American lead scrap remained unchanged, including Scrap Auto Batteries.
| Lead Grade | Weekly Change | % Change |
|---|---|---|
| Scrap Auto Batteries | → 0 | → Flat |
International comparison: China → Flat | India ↑1.56%
Zinc Scrap Moves Lower
COMEX zinc futures closed October 8 at US$3,711.20 per metric ton, down US$15.53 per metric ton, or ↓0.42%. The LME three-month zinc contract closed at US$3,718.50 per tonne.
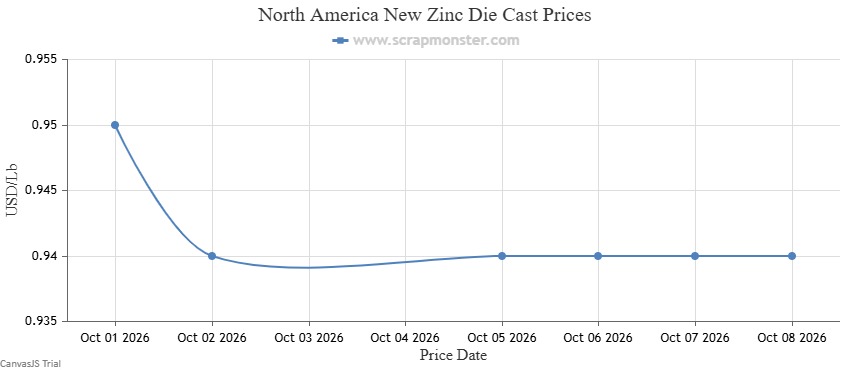
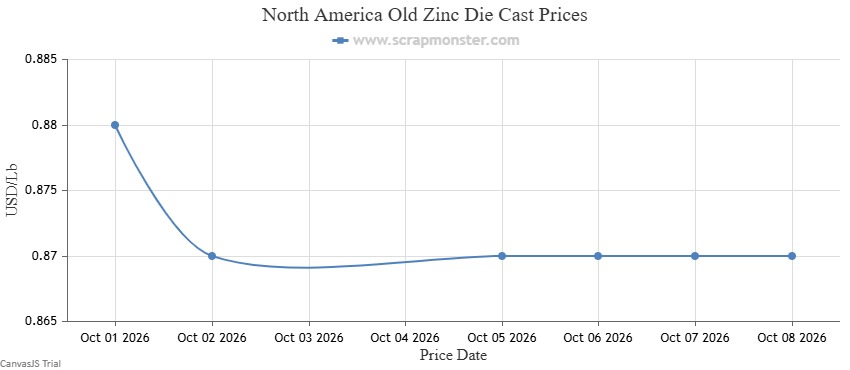
North American zinc scrap declined across the tracked die-cast benchmarks. New Zinc Die Cast fell ↓1¢/lb, or ↓1.05%, while Old Zinc Die Cast declined ↓1¢/lb, or ↓1.14%.
| Zinc Grade | Weekly Change | % Change |
|---|---|---|
| New Zinc Die Cast | ↓1¢/lb | ↓1.05% |
| Old Zinc Die Cast | ↓1¢/lb | ↓1.14% |
International comparison: China ↓0.28% | India ↑0.61%
Steel Mostly Flat as Prime Grades Gain
The closing prices of selected LME steel contracts on October 8 were US$393 per tonne for Steel Scrap CFR Turkey, US$587 per tonne for Rebar FOB Turkey and US$402.20 per tonne for Steel Scrap CFR India.
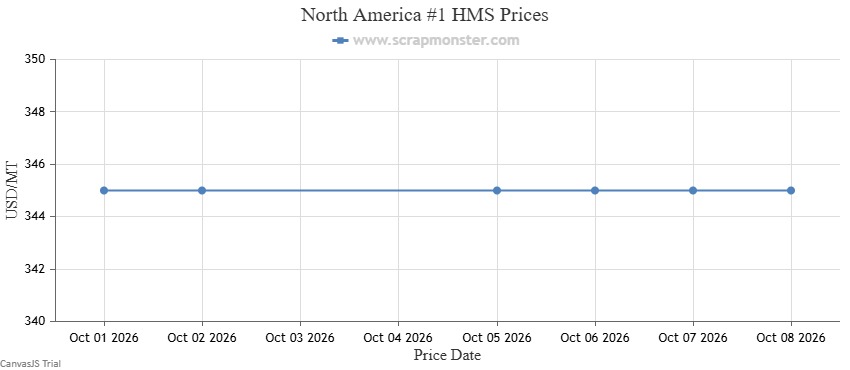
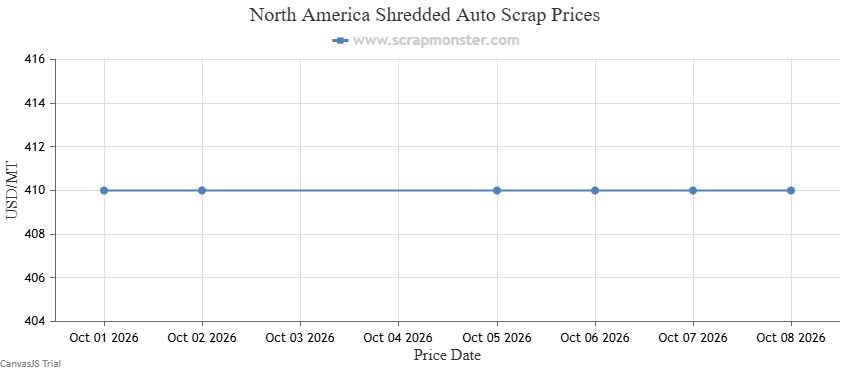
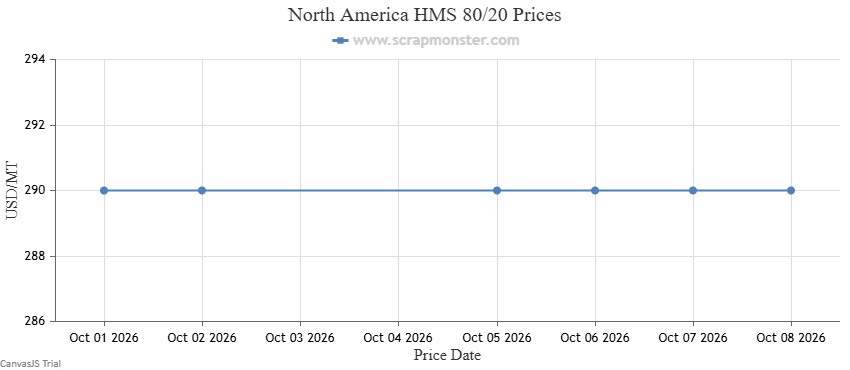
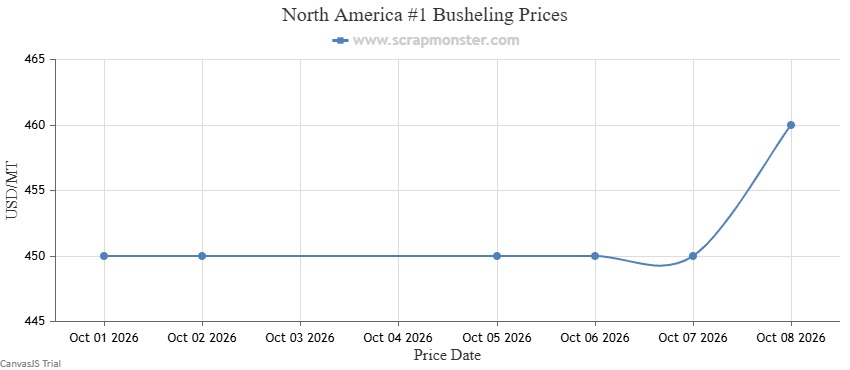
North American ferrous scrap pricing was largely unchanged. #1 HMS, Shredded Auto Scrap and HMS 80/20 held steady in the principal benchmark comparison, while #1 Busheling increased ↑$10/MT, or ↑2.22%. #1 Bundle also gained ↑$10/MT, or ↑2.33%.
U.S. raw steel production totaled 1.801 million net tons in the week ended October 3, ↓2.4% from the previous week but ↑4.8% above the same period in 2025. Capability utilization fell to 78.3% from 80.5% a week earlier.
Regional production: Southern district — 802,000 net tons; Great Lakes — 522,000; Midwest — 282,000; Northeast — 126,000; West — 69,000.
| Steel Grade | Weekly Change | % Change |
|---|---|---|
| #1 HMS | → 0 | → Flat |
| Shredded Auto Scrap | → 0 | → Flat |
| HMS 80/20 | → 0 | → Flat |
| #1 Bundle | ↑$10/MT | ↑2.33% |
| #1 Busheling | ↑$10/MT | ↑2.22% |
Regional Steel Movements
East Coast: Shredded Auto Scrap, HMS 80/20, Structural Steel, #1 HMS and Sheet Metal remained unchanged. #1 Bundle and #1 Busheling each gained ↑$10/MT.
Midwest: #1 HMS increased ↑$10/MT, while #1 Busheling posted a similar ↑$10/MT gain.
West Coast: Ferrous scrap remained broadly stable, with #1 HMS and #1 Busheling among the grades posting gains from the prior week.
International comparison: China → Flat
Stainless Steel Remains Mixed
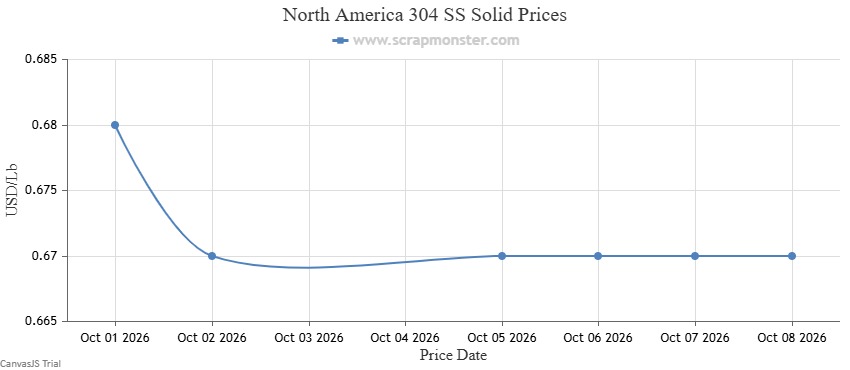
North American stainless steel scrap remained uneven. 201 SS held steady, while 304 SS Solid fell ↓1¢/lb, or ↓1.47%, across the reported regional comparisons.
| Stainless Steel Grade | Weekly Change | % Change |
|---|---|---|
| 304 SS Solid | ↓1¢/lb | ↓1.47% |
| 201 SS | → 0 | → Flat |
The 304 SS Solid decline was reported across the East Coast, Midwest and West Coast comparisons during the week.
International comparison: China ↓0.44%
What to Watch Next Week
United States
- Wednesday, October 14: September Consumer Price Index.
- Thursday, October 15: September Producer Price Index and Advance Retail Sales.
- Friday, October 16: Industrial Production and Capacity Utilization.
Europe
- Tuesday, October 13: Germany final September CPI.
- Thursday, October 15: United Kingdom monthly GDP and industrial-production data.
Asia
- Monday, October 12: India September CPI.
- Wednesday, October 14: China September CPI.
Market read: The week's data do not support a single broad directional call for North American scrap. Aluminum, zinc and selected stainless grades weakened, copper diverged sharply by region, and most ferrous benchmarks remained unchanged. Next week's inflation and industrial data will provide additional context for underlying metals demand and futures markets.