 By

Steel Scrap Jumps $10-$15/MT as Copper Falls 15¢/Lb
North American scrap markets moved in sharply different directions during October 16-22, with steel prices rising $10-$15 per metric ton and stainless steel strengthening, while the major clean copper grades fell 15¢/lb. Aluminum was mostly steady, brass and zinc weakened, and lead remained unchanged.
By Carolina Curiel
Published October 23, 2026
Reporting period: October 16-22, 2026
Key Points
- Copper: Major clean grades fell 15¢/lb, while several secondary grades were unchanged.
- Aluminum: Most benchmarks held steady; E.C. Aluminum Wire and Mixed Aluminum Turnings moved higher.
- Brass/Bronze: Red Brass and Yellow Brass declined 4¢/lb in the primary North American benchmarks.
- Lead: Scrap auto battery prices remained unchanged.
- Zinc: New and Old Zinc Die Cast each declined 1¢/lb.
- Steel: Ferrous benchmarks rose $10-$15/MT, the strongest broad move of the week.
- Stainless Steel: Most monitored grades advanced, while 201 SS and 301 SS remained unchanged.
MONTREAL (Scrap Monster): North American scrap markets produced one of the clearest sector splits of recent weeks during the October 16-22 period, according to the Scrap Monster Price Index.
Clean copper moved lower across the major grades, while steel finally broke out of an extended stretch of largely unchanged benchmarks. Stainless steel also strengthened, aluminum produced selective gains, and brass/bronze and zinc finished lower.
Copper scrap remained under pressure. Xmas Lights recorded the steepest percentage decline among the monitored copper categories, falling 1¢/lb, or ↓2.50%. Cu/Al Radiators, Cu/Al Radiators/Fe and Cu/Al Radiator Ends remained unchanged.
Aluminum scrap showed a modest positive bias even though most grades were unchanged. Mixed Aluminum Turnings led the category with a ↑1.59% weekly increase, while E.C. Aluminum Wire also advanced.
Brass and bronze reversed the previous week's positive trend and moved modestly lower. Lead scrap remained broadly steady, while zinc scrap declined across the key North American die-cast grades.
The week's strongest move came from steel scrap, where the listed benchmarks increased by $10-$15/MT. Stainless steel also moved higher across most grades, although 201 SS and 301 SS remained unchanged.
Pricing note: These are ScrapMonster benchmark buying-price movements. Local quotations can vary by grade, quantity, quality, region and individual buyer conditions.
ScrapMonster Edge: This Was a Rotation, Not a Broad Rally
The most useful way to read this week is not simply “mixed.” Market leadership changed.
Steel and stainless moved higher while copper, brass and zinc weakened. Aluminum showed only limited gains and lead remained flat.
| Market | Weekly Direction | Signal |
|---|---|---|
| Steel | ↑3.41% | Strongest broad-based move |
| Stainless Steel | ↑1.49% | Most grades advanced |
| Aluminum | ↑0.19% | Selective gains, mostly steady |
| Lead | → Flat | No North American battery-scrap change |
| Copper | ↓1.09% to ↓2.50% | Broad clean-copper weakness |
| Brass/Bronze | ↓1.09% | Reversed prior-week gains |
| Zinc | ↓1.10% | Die-cast grades moved lower |
For yards and traders, the takeaway is that broad market direction mattered less this week than metal mix. Ferrous exposure strengthened materially while higher-purity copper and several alloy-linked categories moved the other way.
Non-Ferrous Scrap: Market Drivers
Copper Scrap: Exchange Volatility and Supply Constraints
Copper scrap prices remain sensitive to COMEX and LME movements, mine-supply disruptions and uncertainty surrounding international trade flows. Longer-term demand from power-grid expansion, electrification and data-centre infrastructure remains supportive, although short-term exchange corrections can restrain physical scrap buying.
Aluminum Scrap: Industrial Demand and Feedstock Availability
Aluminum scrap markets continue to face uneven automotive and extrusion demand. At the same time, imported scrap availability remains a sourcing issue for secondary producers in some regions. That combination of softer downstream demand and uneven feedstock availability is creating divergent regional pricing.
Brass and Bronze Scrap: Copper, Zinc and Processing Margins
Brass and bronze remain closely linked to copper and zinc benchmarks, alloy-manufacturing demand and suitable scrap availability. Cautious manufacturing purchases and tighter processing margins can limit turnover, while stronger underlying metals prices may encourage suppliers to hold material.
Lead Scrap: Battery Replacement Demand
Lead scrap demand remains closely connected to automotive replacement batteries, industrial backup-power systems and secondary lead smelting. Stable replacement demand can support collection and recycling, although exchange prices, smelter buying and regional availability still influence physical scrap markets.
Zinc Scrap: Galvanizing Demand and Smelter Economics
Zinc scrap demand reflects activity in galvanized steel, construction and manufacturing as well as the economics of primary zinc production. Changes in smelter margins and raw-material availability can quickly alter secondary-feedstock demand.
International Trade Policy: Export Restrictions and Tariffs
Potential European Union restrictions on scrap exports to certain non-OECD destinations continue to create uncertainty for established non-ferrous recycling routes. Tariffs, import regulations and changing trade flows could redirect material and alter regional competition for scrap.
Non-ferrous market perspective: Copper's supply outlook, aluminum feedstock availability and potential changes to international scrap trade remain among the most important variables to monitor. This week's data show that longer-term structural support does not prevent sharp short-term divergence between individual metals.
Copper Scrap Prices
- COMEX Copper Futures closed at USD 6.4040/lb on October 22, 2026, down approximately 15¢, or ↓2.33%, from the prior week.
- The LME Copper 3-month contract closed at $14,078.00/tonne.
North American Market Highlights
North American copper scrap prices finished the week broadly weaker. #1 Copper Bare Bright declined 15¢/lb, or ↓2.33%. #1 Copper Wire and Tubing and #2 Copper Wire and Tubing also fell 15¢/lb.
Charts
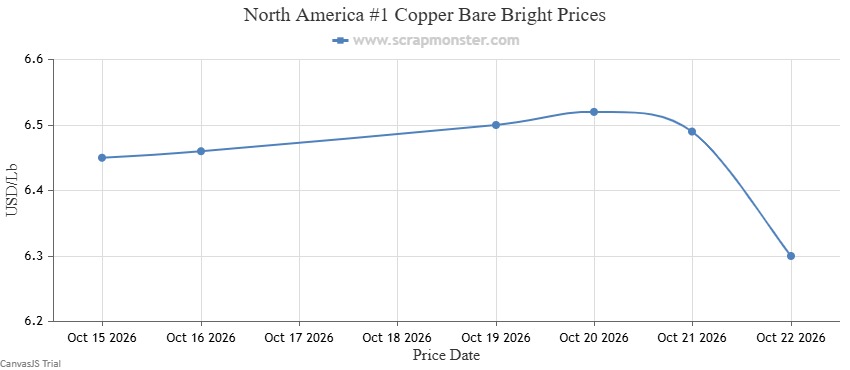
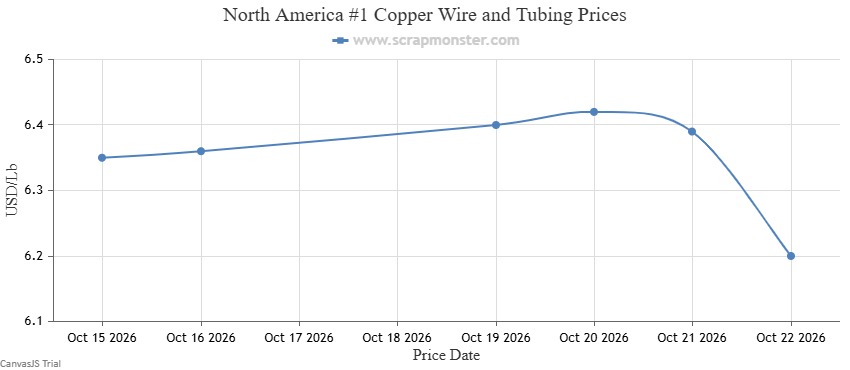
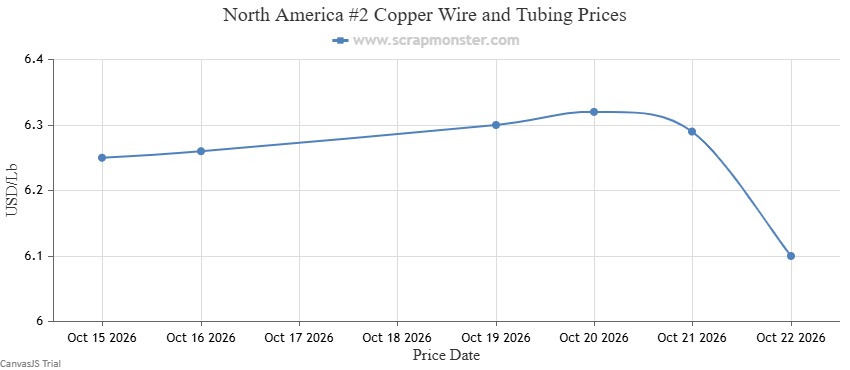
The table below outlines the week-on-week movements in the major clean copper grades.
| Category | Price Change | % Change |
|---|---|---|
| #1 Copper Bare Bright | -0.15 | -2.33% |
| #1 Copper Wire and Tubing | -0.15 | -2.36% |
| #2 Copper Wire and Tubing | -0.15 | -2.40% |
Access the Daily Scrap Metal Price Report Hub →
Track real-time prices through the US Scrap Price Index.
USA East Coast Copper Scrap Prices
#1 Copper Bare Bright declined 15¢/lb, or ↓2.33%. #1 Copper Wire and Tubing fell 15¢/lb, or ↓2.36%, while #2 Copper Wire and Tubing was down 15¢/lb, or ↓2.40%.
USA Midwest Copper Scrap Prices
#1 Copper Bare Bright fell 15¢/lb, or ↓2.35%. #1 Copper Wire and Tubing declined 15¢/lb, or ↓2.39%, while #2 Copper Wire and Tubing decreased 15¢/lb, or ↓2.43%.
USA West Coast Copper Scrap Prices
#1 Copper Bare Bright declined 15¢/lb, or ↓2.29%. #1 Copper Wire and Tubing fell 15¢/lb, or ↓2.33%, while #2 Copper Wire and Tubing dropped 15¢/lb, or ↓2.36%.
International Comparison: Copper
China Copper Scrap Prices
All copper grades except Copper Transformer Scrap declined week over week. #2 Copper Wire and Tubing recorded the sharpest decline at ↓1.16%, followed by #1 Copper Wire and Tubing at ↓1.15%.
India Copper Scrap Prices
All monitored copper scrap categories declined. Copper Sheet Cutting posted the largest weekly loss, falling INR 43,000/tonne, or ↓4.48%.
Aluminum Scrap Prices
- COMEX Aluminum Futures closed at USD 3,009.45/MT on October 22, up $24.45, or ↑0.82%, from the prior week's USD 2,985.00/MT close.
- The LME Aluminum 3-month contract closed at $3,009.45/tonne.
North American Market Highlights
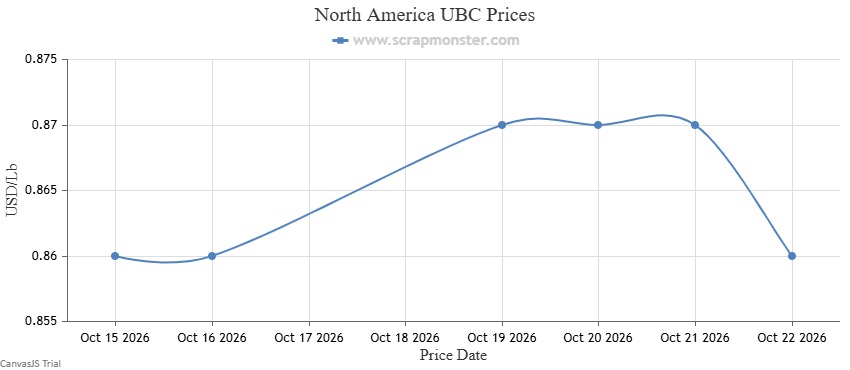
Aluminum remained mostly stable. E.C. Aluminum Wire gained ↑0.74%. Mixed Aluminum Turnings posted the strongest percentage increase in the broader category at ↑1.59%. 6063 Extrusions, Old Cast and UBC finished unchanged.
Charts
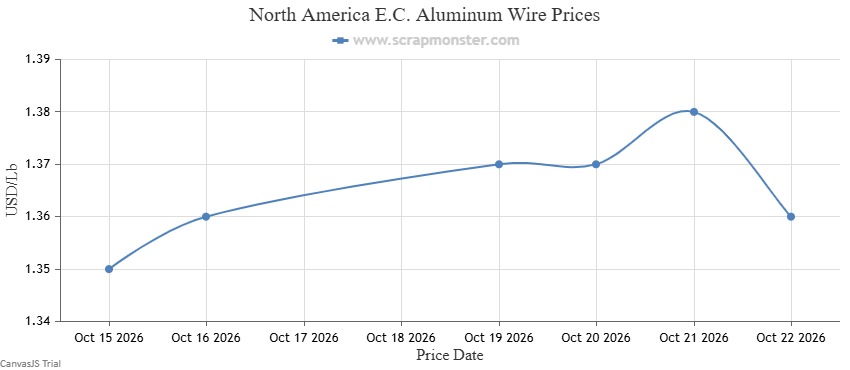
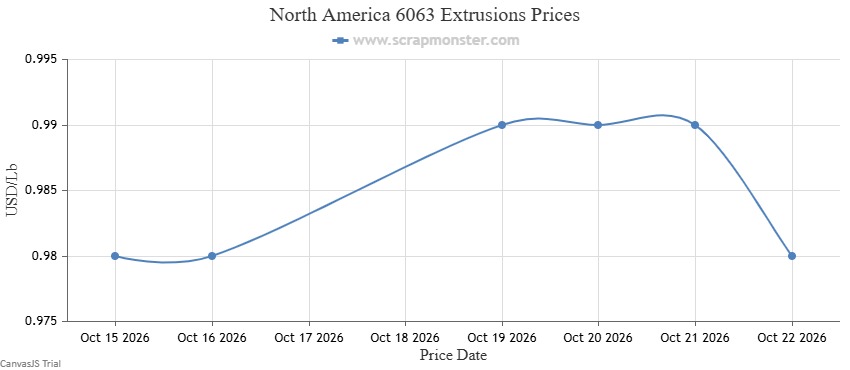
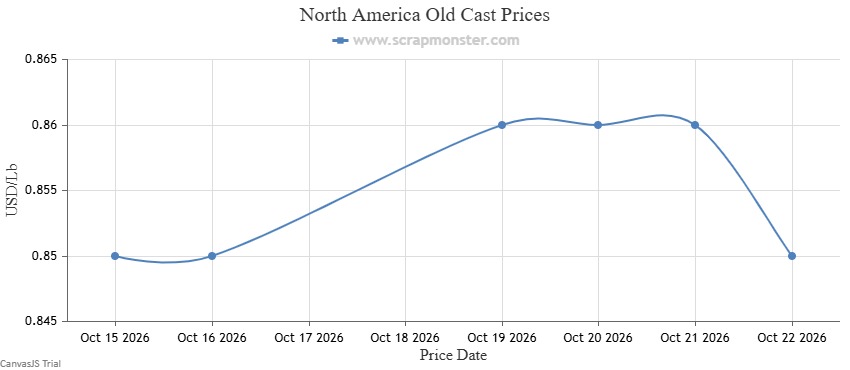
| Category | Price Change | % Change |
|---|---|---|
| E.C. Aluminum Wire | +0.01 | +0.74% |
| 6063 Extrusions | 0 | Flat |
| Old Cast | 0 | Flat |
| UBC | 0 | Flat |
Access the Daily Scrap Metal Price Report Hub →
Track real-time prices through the US Scrap Price Index.
USA East Coast Aluminum Scrap Prices
E.C. Aluminum Wire gained ↑0.74%. 6063 Extrusions, Old Cast and UBC remained unchanged.
USA Midwest Aluminum Scrap Prices
E.C. Aluminum Wire rose 1¢/lb. 6063 Extrusions, Old Cast and UBC were unchanged from the previous week's closing benchmarks.
USA West Coast Aluminum Scrap Prices
E.C. Aluminum Wire increased ↑0.74%, while 6063 Extrusions, Old Cast and UBC finished flat.
International Comparison: Aluminum
China Aluminum Scrap Prices
All monitored aluminum categories recorded modest weekly increases. Old Cast and Old Sheet posted the largest moves, each rising CNY 250/MT, or ↑1.20%.
India Aluminum Scrap Prices
All monitored aluminum scrap categories remained unchanged.
Brass/Bronze Scrap Prices
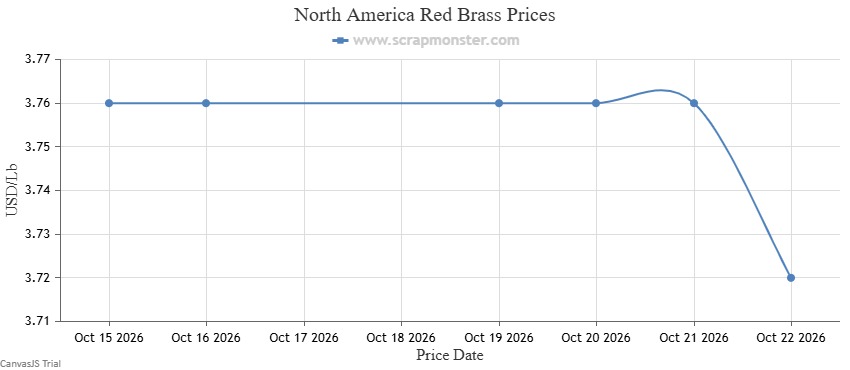
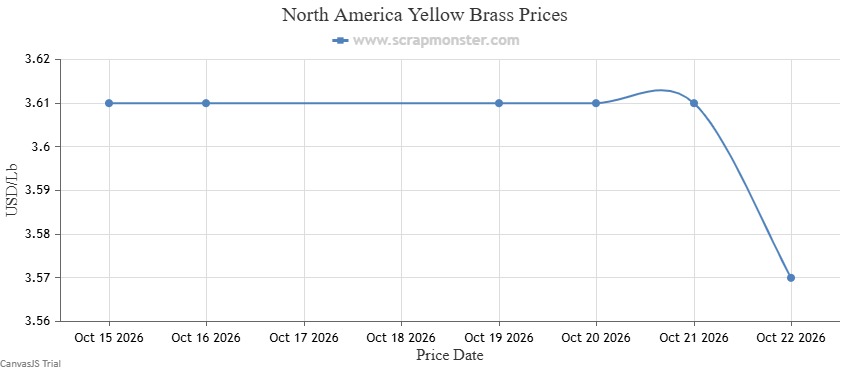
North American brass and bronze moved modestly lower. Yellow Brass declined 4¢/lb, or ↓1.11%, while Red Brass fell 4¢/lb, or ↓1.06%.
Charts
| Category | Price Change | % Change |
|---|---|---|
| Red Brass | -0.04 | -1.06% |
| Yellow Brass | -0.04 | -1.11% |
USA East Coast Brass/Bronze Scrap Prices
Red Brass and Yellow Brass each declined 4¢/lb.
USA Midwest Brass/Bronze Scrap Prices
Red Brass declined 4¢/lb. Yellow Brass also fell 4¢/lb, or ↓1.14%.
USA West Coast Brass/Bronze Scrap Prices
West Coast Red Brass and Yellow Brass remained unchanged, diverging from the weaker East Coast and Midwest readings.
International Comparison: Brass/Bronze
China Brass/Bronze Scrap Prices
All monitored brass/bronze categories declined. Red Brass and Yellow Brass each fell CNY 250/MT.
India Brass/Bronze Scrap Prices
All monitored grades declined. Brass Cuttings recorded the largest weekly loss, falling INR 11,000/tonne, or ↓2.54%.
Lead Scrap Prices
- COMEX Lead Futures rose USD 21.45/ton, or ↑1.14%, to close at USD 1,904.43/ton on October 22.
- The LME Lead 3-month contract closed at $1,897.50/tonne.
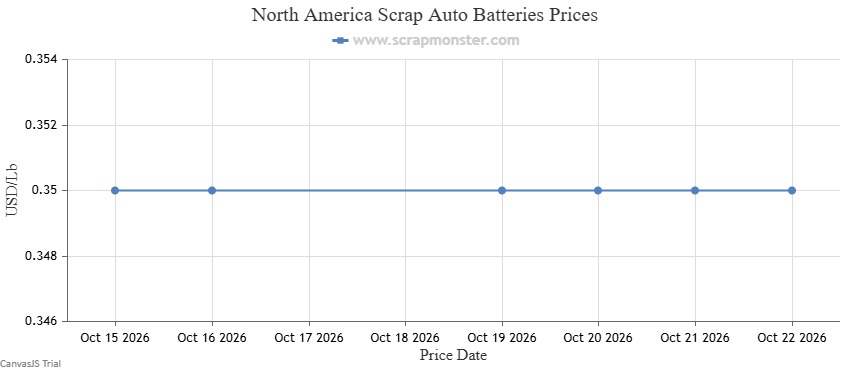
North American lead scrap remained flat. Scrap Auto Batteries recorded no weekly movement, reflecting relatively balanced physical-market conditions.
Chart
| Category | Price Change | % Change |
|---|---|---|
| Scrap Auto Batteries | 0 | Flat |
USA East Coast Lead Scrap Prices
Scrap Auto Batteries remained unchanged as of October 22.
USA Midwest Lead Scrap Prices
Scrap Auto Batteries remained stable week over week.
USA West Coast Lead Scrap Prices
Scrap Auto Batteries recorded no weekly change.
International Comparison: Lead
China Lead Scrap Prices
Auto Battery prices remained unchanged. Soft Lead increased ↑0.37%, while #2 Lead Scrap rose ↑0.38%.
India Lead Scrap Prices
Lead Ingot Scrap increased INR 1,000/ton, or ↑0.52%.
Zinc Scrap Prices
- COMEX Zinc Futures closed at USD 3,676.45/MT, down USD 0.20/MT, or ↓0.01%.
- The LME Zinc 3-month contract closed at $3,671.00/tonne.
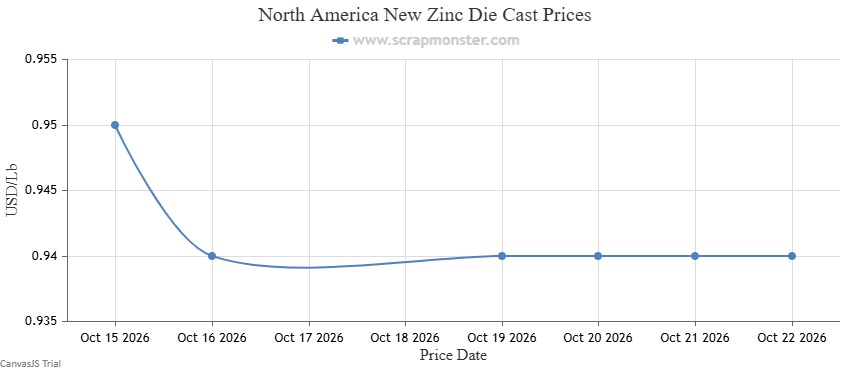
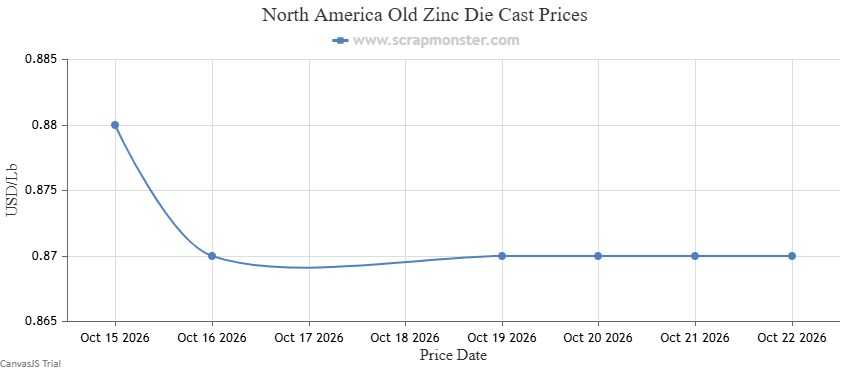
North American zinc scrap prices weakened. New Zinc Die Cast fell 1¢/lb, or ↓1.05%, while Old Zinc Die Cast also declined 1¢/lb, or ↓1.14%.
Charts
| Category | Price Change | % Change |
|---|---|---|
| New Zinc Die Cast | -0.01 | -1.05% |
| Old Zinc Die Cast | -0.01 | -1.14% |
USA East Coast Zinc Scrap Prices
New Zinc Die Cast and Old Zinc Die Cast each declined 1¢/lb.
USA Midwest Zinc Scrap Prices
Both New Zinc Die Cast and Old Zinc Die Cast fell 1¢/lb during the week ended October 22.
USA West Coast Zinc Scrap Prices
New Zinc Die Cast and Old Zinc Die Cast each recorded a 1¢/lb weekly decline.
International Comparison: Zinc
China Zinc Scrap Prices
Shred Zinc Scrap remained unchanged during the week ended October 22.
India Zinc Scrap Prices
Tin Slab remained flat, while Zinc Slab increased ↑0.72%.
Ferrous Scrap: Market Drivers
HMS Scrap: Turkish Import Demand and Tight Supply
HMS prices are receiving support from low mill inventories and limited availability of alternative metallic inputs in Türkiye. Cautious procurement and pressure on rebar sales are nevertheless limiting mills' willingness to chase higher offers.
Shredded Scrap: Collection Volumes and Domestic Mill Demand
Shredded scrap remains sensitive to obsolete-scrap collection and EAF mill demand. Tighter availability can support pricing, while mill maintenance and softer finished-steel orders can restrain purchasing volumes.
Busheling Scrap: Manufacturing Activity and Prime Scrap Supply
Busheling supply is tied closely to automotive, appliance and industrial production. Cleaner chemistry and lower residual content continue to support demand for prime scrap, particularly where manufacturing scrap generation is limited.
#1 Bundle Scrap: Automotive and Manufacturing Generation
#1 Bundle prices reflect the availability of clean compressed steel offcuts from stamping plants and manufacturing operations. Competition for prime material can strengthen prices when mill procurement requirements increase.
Cast Iron Scrap: Foundry Demand and Industrial Production
Cast iron scrap demand depends on foundries and industrial-equipment manufacturing. Weak industrial orders can restrain buying, while localized shortages of suitable foundry-grade material can support premiums.
Seasonal Scrap Supply: Winter Collection and Mill Procurement
Scrap flows can tighten toward year-end as colder weather, shorter working periods and collection disruptions affect some regions. Lower yard inventories may strengthen mill competition for material, although planned maintenance can offset some of that pressure.
Ferrous market perspective: Ferrous scrap enters the final quarter of 2026 with stronger North American mill requirements and tighter conditions in selected grades, but weak steel margins in some international markets, cautious buying and subdued downstream demand remain important constraints.
Steel Scrap Prices
Selected LME 2-month steel contracts closed October 22 at:
| Contract | Close |
|---|---|
| Steel Scrap CFR Turkey (Platts) | $391.50/tonne |
| Steel Rebar FOB Turkey (Platts) | $585.00/tonne |
| Steel Scrap CFR India (Platts) | $395.00/tonne |
North American Market Highlights
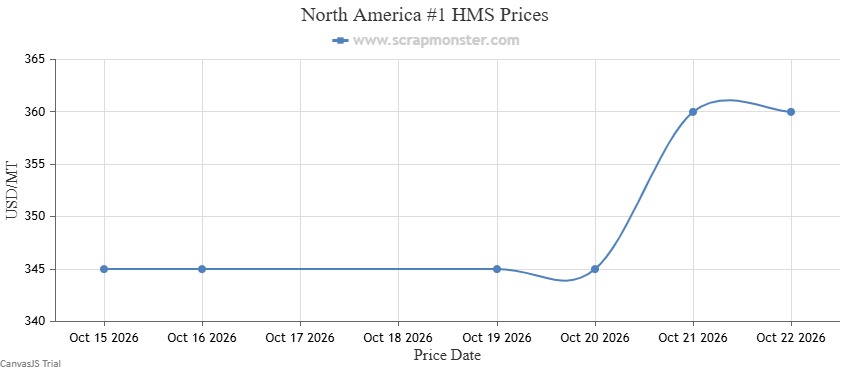
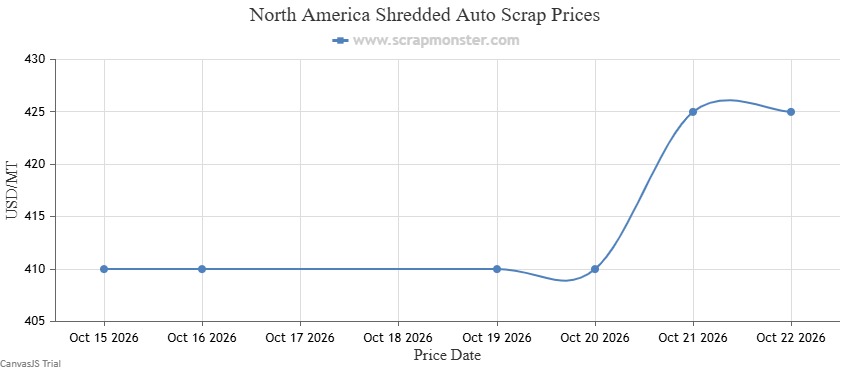
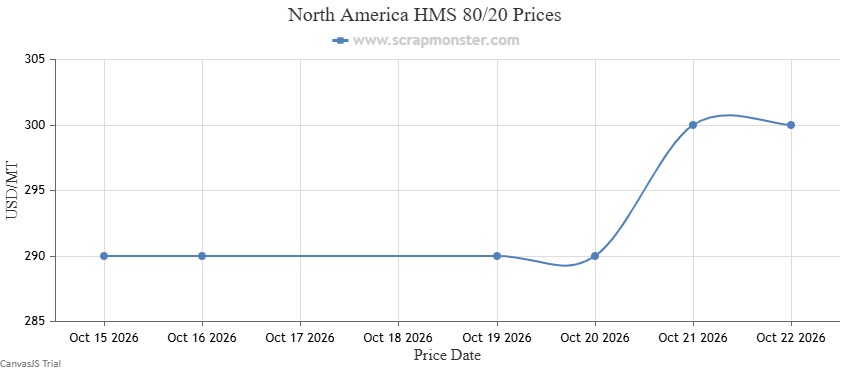
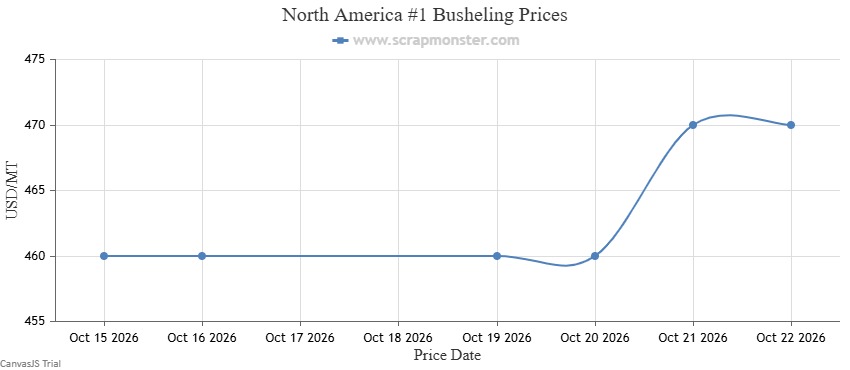
Steel delivered the week's strongest broad move after several sessions of stable benchmarks. #1 HMS rose $15/MT, or ↑4.35%. Shredded Auto Scrap also gained $15/MT, while HMS 80/20 and #1 Busheling increased $10/MT.
U.S. raw steel production totaled 1.870 million net tons in the week ended October 17, up ↑4.10% from the previous week and ↑8.60% from a year earlier. Capability utilization increased to 80.9%, from 77.8% the previous week.
Regional production: Northeast 131,000 NT; Great Lakes 520,000 NT; Midwest 313,000 NT; Southern 842,000 NT; Western 64,000 NT.
Charts
| Category | Price Change ($/MT) | % Change |
|---|---|---|
| #1 HMS | +15 | +4.35% |
| Shredded Auto Scrap | +15 | +3.66% |
| HMS 80/20 | +10 | +3.45% |
| #1 Busheling | +10 | +2.17% |
USA East Coast Steel Scrap Prices
Ferrous prices strengthened across the monitored grades. #1 HMS and Structural Steel recorded the largest percentage gains, each rising ↑4.35%.
USA Midwest Steel Scrap Prices
#1 HMS and Shredded Auto Scrap each increased $15/MT, while HMS 80/20 and #1 Busheling gained $10/MT.
USA West Coast Steel Scrap Prices
Steel benchmarks moved higher across the Index. #1 HMS and Structural Steel recorded the largest jumps, each gaining $15/MT, or ↑4.35%.
International Comparison: Steel
China: Flat.
#1 HMS and Cast Iron Scrap remained unchanged from the previous week's levels.
Stainless Steel Scrap Prices
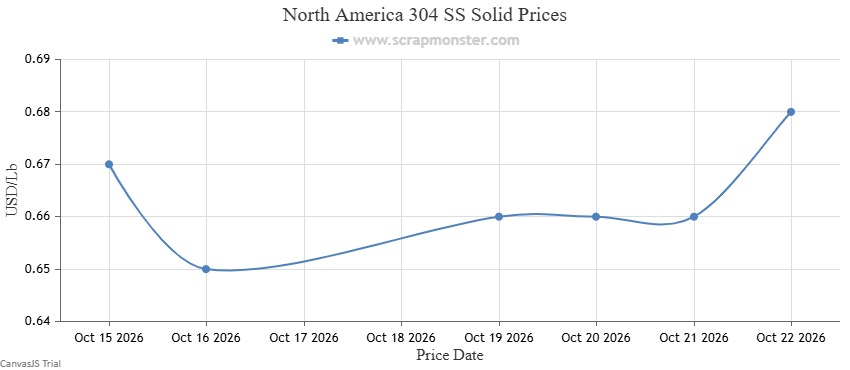
Stainless steel strengthened during the week, with most grades posting moderate increases. 304 SS Turning recorded the strongest monitored North American percentage gain at ↑1.75%. 201 SS and 301 SS remained unchanged.
Chart
| Category | Price Change | % Change |
|---|---|---|
| 304 SS Solid | +0.01 | +1.49% |
USA East Coast Stainless Steel Scrap Prices
304 SS Solid increased ↑1.49%.
USA Midwest Stainless Steel Scrap Prices
304 SS Solid gained 1¢/lb, or ↑1.49%.
USA West Coast Stainless Steel Scrap Prices
304 SS Solid rose 1¢/lb, or ↑1.49%.
International Comparison: Stainless Steel
China: ↑1.78%.
All listed Chinese stainless steel grades moved higher. 310 SS posted the strongest increase at ↑2.80%, followed by 316 SS Solid at ↑2.45%.
Weekly Market Drivers
| Theme | ScrapMonster Coverage |
|---|---|
| Steel Mill Investment | U.S. Steel to Invest More Than $2 Billion in New Hot Strip Mill in Braddock |
| Site Redevelopment | Former Alton Steel Mill Eyed for 200-MW Data Center |
| Tariffs and Domestic Demand | Canadian Steelmakers Shift Toward Domestic Demand as Tariffs Reshape Market |
| U.S. Steel Supply | U.S. Steel Supply Tightens as Nickel Rebounds Above $16,000 |
| Earnings and Outlook | Steel Dynamics Q3 Profit Jumps as Steel Shipments Hit Record Cleveland-Cliffs Q3 EBITDA Hits $612M as Shipments Rise CMC Q4 Core EBITDA Jumps 35% on Strong Steel Margins |
| China Steel Output | China Steel Output Rises as Mill Profitability Falls to 7% |
| Metal Recycling and Compliance | DOT Hazmat Rules for Shipping Scrap Metal: 2026 Guide BIR Malaga to Examine Waste Rules and Scrap Trade Risks |
| Canadian Steel Prices | Canada Steel Prices Rise 45% as Import Curbs Reshape Market |
Global Comparison: U.S. vs. China and India
| Metal | U.S. | China | India |
|---|---|---|---|
| Copper | ↓1.09% to ↓2.50% | ↓1.14% | ↓3.35% |
| Aluminum | ↑0.19% | ↑1.05% | Flat |
| Brass/Bronze | ↓1.09% | ↓0.60% | ↓2.33% |
| Zinc | ↓1.10% | Flat | ↑0.36% |
| Steel | ↑3.41% | Flat | - |
| Stainless Steel | ↑1.49% | ↑1.78% | - |
Industry View
“The main drivers of this October were strong US mill demand and order books, an export market that had risen over the course of September but has now pulled back slightly, and the season.”
Market Outlook
HMS Scrap: Moderate Upside Potential
International HMS prices could remain supported by Turkish mill procurement and competition for export cargoes. Weak rebar sales and limited mill liquidity may nevertheless prevent buyers from accepting sustained increases.
Shredded Scrap: Firm Prices Amid Supply Constraints
Shredded scrap could remain relatively firm if collection volumes stay limited and EAF mills maintain purchasing requirements. A slowdown in steel production or improved imported scrap availability could moderate gains.
Busheling Scrap: Quality Premiums Likely to Persist
Prime busheling could remain supported by competition for clean, low-residual feedstock and comparatively tight inventories. Weaker automotive production or softer industrial output would limit that support.
#1 Bundle Scrap: Recovery Depends on Mill Demand
#1 Bundle could strengthen gradually if mill procurement increases and manufacturing activity supports consistent demand for clean production scrap. The durability of any improvement will depend on finished-steel order books and mills' ability to pass higher input costs through to customers.
Cast Iron Scrap: Uneven Performance Expected
Cast iron pricing is likely to remain mixed because foundry demand, machinery production and material availability vary by region. Weak industrial orders could restrain purchases, while localized shortages may support selected grades.
Regional Markets: Divergence Likely to Continue
European scrap markets may remain relatively stable, with logistics constraints supporting selected grades while uneven steel demand limits broader gains. In Asia, freight and raw-material costs may provide support, although weak downstream consumption and pressure on steel-mill profitability remain downside risks.
Overall outlook: The near-term scrap market is likely to remain firm but volatile. Medium-term direction will depend on steel mill procurement, finished-steel demand, scrap availability and transportation costs. The latest data favour selective gains over a broad-based rally.
Operator Takeaway
Ferrous: The week's $10-$15/MT move is meaningful because it follows several sessions of stable benchmarks and coincides with stronger U.S. raw steel output.
Copper: A 15¢/lb weekly decline in clean grades means yards should not assume that longer-term copper supply concerns will translate into uninterrupted near-term scrap-price strength.
Aluminum: The market is still grade-specific. E.C. Aluminum Wire and Mixed Aluminum Turnings improved, but broad participation was absent.
Bottom line: Metal mix matters more than the headline this week. Operators exposed to ferrous and stainless saw a very different market from those concentrated in clean copper, brass or zinc.
Watchlist for the Upcoming Week
United States
- Monday, October 26: Chicago Fed National Activity Index and Dallas Fed Manufacturing Index.
- Tuesday, October 27: September Durable Goods Orders and October Consumer Confidence.
- Wednesday, October 28: Federal Reserve interest-rate decision and press conference following the October 27-28 FOMC meeting.
- Thursday, October 29: Q3 GDP advance estimate and September Personal Income and Outlays, including Core PCE.
- Friday, October 30: Q3 Employment Cost Index and October Chicago PMI.
Europe: EU and UK
- Tuesday: ECB Bank Lending Survey, Eurozone money supply and France consumer confidence.
- Thursday: ECB monetary-policy decision and Eurozone consumer confidence final reading.
- Friday: Eurozone and Germany Q3 GDP advance estimates, preliminary October German CPI and Eurozone unemployment.
Asia and Oceania
- Wednesday: Australia Consumer Price Index.
- Thursday: Japan consumer confidence, retail sales, unemployment and September industrial production.
- Friday: Bank of Japan monetary-policy decision and policy statement.
- Saturday: China NBS Manufacturing and Non-Manufacturing PMIs for October.
Weekly Scrap Metal Market Videos
Watch ScrapMonster's weekly market videos for North American scrap-price movements, benchmark trends and industry context across the major metal categories.
Frequently Asked Questions
How did North American scrap metal prices perform during October 16-22, 2026?
The market diverged sharply. Steel and most stainless grades increased, clean copper, brass and zinc declined, aluminum was mostly stable with selected gains, and lead remained unchanged.
Which market recorded the strongest weekly move?
Steel scrap recorded the clearest broad-based advance. Major benchmark grades increased by $10-$15 per metric ton, with #1 HMS rising 4.35%.
How much did major clean copper scrap fall?
#1 Copper Bare Bright, #1 Copper Wire and Tubing and #2 Copper Wire and Tubing each declined 15¢/lb in the primary benchmark series.
Did aluminum scrap prices rise?
Only selectively. E.C. Aluminum Wire gained 1¢/lb and Mixed Aluminum Turnings posted the strongest percentage increase, while 6063 Extrusions, Old Cast, UBC and most other grades were unchanged.
What happened to stainless steel scrap?
Most stainless grades increased. 304 SS Turning led the weekly percentage gains, while 201 SS and 301 SS remained unchanged.
What is the main issue to watch next week?
The combination of the Federal Reserve decision, U.S. GDP and inflation data, the ECB and Bank of Japan meetings, and China manufacturing data could affect currencies, exchange-traded metals and the broader demand outlook. For physical scrap, mill procurement and material availability remain the more immediate drivers.
Also Read
Explore More
Daily Reports | Scrap Monster Price Index | US Scrap Metal Prices | Weekly Reports
Related Resources
Copper Scrap Prices | Aluminum Scrap Prices | Steel Scrap Prices | Brass Scrap Prices | Stainless Steel Scrap Prices
Live Pricing and Historical Data
Track real-time prices via our US Scrap Price Index.
Live grade-level prices, historical data, charts and additional market tools are available through ScrapMonster Premium.
Subscribe to Scrap Monster Live Scrap Prices →
Full pricing details, yard finder tools, market analysis and live price charts are available at ScrapMonster.com. ScrapMonster serves more than 100,000 recycling professionals across its market-data and industry-information platforms.