West Fraser Timber faces earnings test as lumber markets stabilize
Rubber and Wood | 2026-10-27 23:45:18
Year-over-year comparisons look more favorable, with the expected loss narrowing 72% from the prior-year period while revenue climbs 8.4%.
 By Paul Ploumis
SEATTLE (Scrap Monster): West Fraser Timber Co Ltd reports third-quarter results on Wednesday, with investors focused on whether the forestry giant can deliver the expected sequential improvement in losses after a disappointing summer quarter that saw both earnings and revenue miss estimates.
Analysts expect the company to post a loss of $0.73 per share on revenue of $1.42 billion for the September quarter. That would represent a modest improvement from the second quarter’s loss of $0.78 per share, though revenue is forecast to edge down slightly from $1.43 billion. Year-over-year comparisons look more favorable, with the expected loss narrowing 72% from the prior-year period while revenue climbs 8.4%.
Analyst sentiment around the Vancouver-based company has remained cautious heading into the report. Potential catalysts include lumber pricing, housing construction and mill productivity, with shares advancing 3.62% on October 22, 2026, though the stock at $70 remains well off its 52-week high of $76.99. EPS estimates have remained flat over the past week, while revenue estimates have been largely stable, declining less than 1% over the past 60 days.
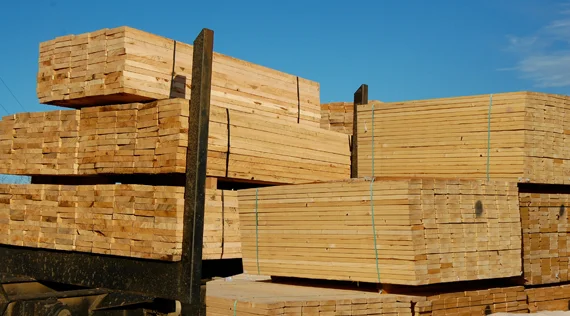
The company operates more than 50 facilities across North America and Europe, producing lumber, oriented strand board, and engineered wood products. Its performance is tightly linked to North American housing activity and commodity lumber prices, which have shown mixed signals in recent months. The North American softwood lumber market in June 2026 was marked by cautious buying and flat benchmark prices, with Western SPF 2x4 held at $490 per thousand board feet.
What Investors Are Watching
The key question is whether West Fraser can demonstrate margin resilience amid an uneven pricing environment. With benchmark lumber prices stabilizing after earlier volatility, investors will scrutinize what realizations the company achieved for its products and whether volume shifts helped offset any pricing headwinds.
Housing market signals will be closely monitored. Lumber demand is driven primarily by residential construction, and any commentary on builder activity or the company’s order file could provide insight into demand trends heading into 2027.
Cost management and mill utilization rates matter significantly in a cyclical downturn. With the company posting a 22% gross margin on trailing revenue of $5.24 billion, investors want to see disciplined production curtailments where necessary and evidence that overhead absorption isn’t deteriorating further.
Last quarter’s results disappointed on both lines. The company reported a loss of $0.78 per share for the quarter ending July 29th, missing the consensus estimate of $0.70, while revenue of $1.43 billion came in below the $1.5 billion forecast.
Wednesday’s report will test whether West Fraser can execute the gradual recovery analysts project, with consensus models calling for improving profitability through 2027. For a company trading at a forward price-to-earnings ratio of negative 17.6 on an expected loss of $3.80 for the full year, the path back to sustained profitability remains the overarching narrative investors are watching.
Courtesy: www.investing.com