 By
SCRAPMONSTER | WEEKLY SCRAP MARKET REPORT
Scrap Metal Prices: Weekly Market Report – October 30–November 5, 2026
Copper recorded steep weekly losses, while U.S. steel scrap strengthened. Aluminum, brass/bronze, zinc and stainless steel weakened; lead remained steady.
By Carolina Curiel | Published: November 6, 2026 | Market period: October 30–November 5, 2026
Weekly Market at a Glance
Copper: ▼ Up to 5.81% across the highlighted grades; select Cu/Al radiator grades unchanged.
Aluminum: ▼ Mostly lower; E.C. Aluminum Wire unchanged.
Brass/Bronze: ▼ Lower across key tracked grades.
Stainless Steel: ▼ Lower in North America; China rose.
Steel: ▲ #1 HMS 4.17%; Shredded Auto Scrap 3.53%, HMS 80/20 3.33%.
Lead: → Unchanged across the reported North American battery scrap benchmark.
Zinc: ▼ Lower for New and Old Zinc Die Cast.
MONTREAL (Scrap Monster): This report examines the latest developments in the North American scrap metal market by tracking price movements across major scrap categories during the week of October 30–November 5, 2026. The analysis is based on data from the Scrap Monster Price Index and highlights week-over-week changes, offering insights into prevailing market trends and pricing dynamics.
SCRAPMONSTER EDGE | WEEKLY MARKET ANALYSIS
Copper Falls While Ferrous Scrap Strengthens
North American #3 Copper-Light Copper declined 5.81% and #2 Copper Wire and Tubing fell 5.71%, while #1 HMS advanced 4.17%. The contrasting movements show that ferrous and non-ferrous scrap did not follow the same pricing direction this week.
Operator takeaway: Assess grade-level exposure and mill buying conditions separately. A stronger ferrous market does not imply equivalent support for copper, brass or aluminum scrap.
Copper scrap prices edged lower during the week, with most grades recording notable decline while a handful of key categories registered no change on the Index. The top losers were #3 Copper- Light Copper and #2 Copper Wire and Tubing, which fell sharply by ↓5.81% and ↓5.71%, respectively, from the previous week. Meanwhile, Cu/Al Radiators, Cu/Al Radiators/Fe, and Cu/Al Radiator Ends held steady.
Aluminum scrap prices posted a modest week-on-week decline on the Scrap Monster Price Index, with most tracked grades moving lower. However, Aluminum Radiators, Aluminum Radiators/Fe, Mixed Aluminum Turnings, Breakage 50% Recovery, Al/Cu Radiators, Al/Cu Radiators/Fe, E.C. Aluminum Wire, and Aluminum Transformers held steay during the week under review.
Brass and bronze scrap prices posted modest declines on the Index, reversing the uptrend witnessed during the previous week. In the meantime, lead scrap markets remained stable, with no price variations reported across key regional markets.
Zinc scrap prices moved lower during the week. New Zinc Die Cast and Old Zinc Die Cast both edged down on the Scrap Monster Price Index, reflecting a softer weekly tone in North American zinc scrap. Meanwhile, the global steel scrap benchmarks edged higher after remaining unchanged for several weeks in a row.
Stainless steel scrap prices in North America recorded a downward trend on the Index during the period under review. However, 201 SS prices remained unchanged week-on-week. Also, Chinese stainless steel scrap market recorded a positive movement during the week.
For full market breakdowns, visit the Daily Scrap Metal Price Report Hub or track real-time prices via the US Scrap Price Index.
NON-FERROUS SCRAP
Market Drivers
Copper – Exchange Price Volatility and Inventory Build-up
Copper prices faced downward pressure amid a broader sell-off in base metals, technology stocks and concerns over near-term industrial demand. Rising LME warehouse inventories and a stronger supply of deliverable metal weighed on sentiment, although tight physical availability in China offered some support.
Aluminum – Limited Price Movement and Cautious Buying
Aluminum prices remained relatively stable compared with other base metals, with the LME benchmark holding onto its previous gains before experiencing modest weakness. Cautious downstream purchasing and steady warehouse inventories limited the scope for a stronger recovery.
Brass and Bronze – Relative Price Resilience
Brass and bronze scrap demonstrated greater resilience than copper during the early part of the week. North American benchmarks recorded modest gains, supported by improved buying interest, although the subsequent weakness in copper prices could restrict further advances.
Stainless Steel – Nickel Market Weakness
Stainless steel scrap faced pressure from softer nickel prices and subdued buying sentiment. The weakness in selected stainless grades contrasted with gains in some other non-ferrous categories, reflecting differences in alloy composition and underlying demand.
Zinc – Gains Offset by Renewed Market Weakness
Zinc prices experienced fluctuations, with an earlier recovery losing momentum amid the broader weakness across base metals. Cautious industrial demand and changing exchange inventories remained important factors influencing zinc scrap valuations.
Lead – Limited Recovery and Battery Scrap Stability
Lead prices showed modest resilience compared with copper and tin, recovering slightly during the latter part of the week. However, subdued demand from battery manufacturers and relatively stable lead scrap buying benchmarks limited the scope for significant price increases.
Overall market assessment: Non-ferrous scrap markets experienced mixed conditions during the week. Copper faced the strongest downward pressure, while aluminum remained comparatively stable and nickel performance differed from copper. Brass and bronze demonstrated resilience, whereas tin and stainless steel faced weaker market sentiment.
COPPER SCRAP PRICES
- COMEX copper futures, December 2026 contract (HGZ6): USD 6.2295/lb at the November 5 close. The original weekly report cites a decline of about 37¢/lb (5.65%) from its prior-week comparison.
- LME Copper 3-month closing price, November 5, 2026: $13,843.50 per metric tonne (LME Closing Prices, not Official Prices).
Market Highlights
North America Copper Scrap Prices: Copper scrap prices moved lower during the week as subdued trading activity and restrained buying interest continued to pressure the market. #1 Copper Wire and Tubing fell by ↓5.63%, followed by #1 Copper Bare Bright , which slipped ↓5.54%. Meanwhile, #2 Copper Wire and Tubing posted the steepest decline among the major grades, dropping ↓5.71% over the previous week.
Historical Price Charts
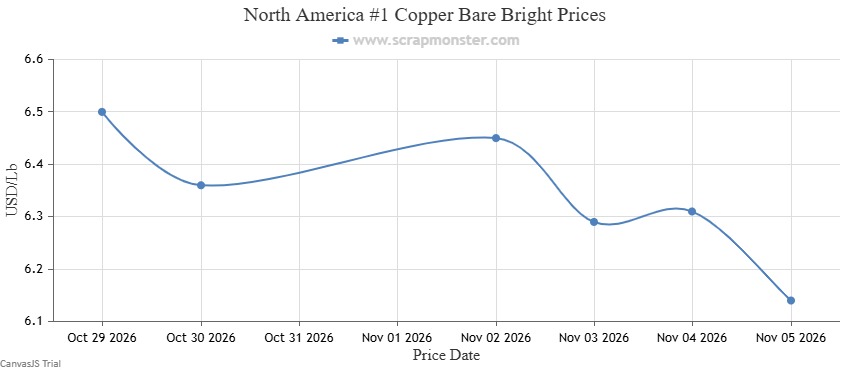
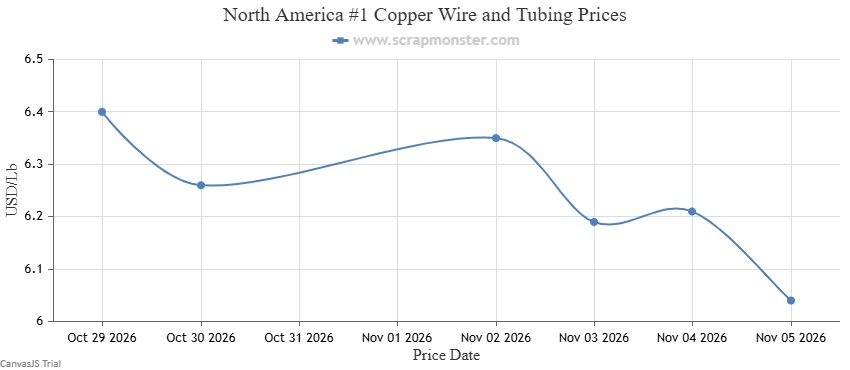
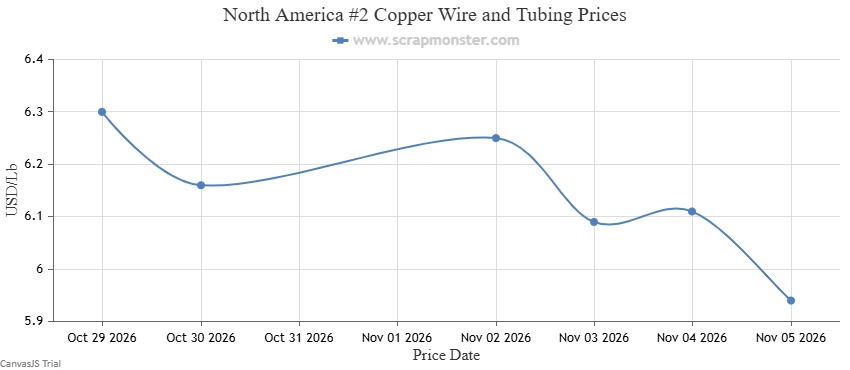
The table below highlights the week-on-week price movements for #1 Copper Bare Bright, #1 Copper Wire and Tubing, and #2 Copper Wire and Tubing.
| Category | Weekly change (USD; source units) | % Change |
| #1 Copper Bare Bright | -0.36 | -5.54% |
| #1 Copper Wire and Tubing | -0.36 | -5.63% |
| #2 Copper Wire and Tubing | -0.36 | -5.71% |
USA East Coast Copper Scrap Prices
Copper scrap prices extended their downward trend on the Scrap Monster Price Index during the week ending November 5, 2026. #1 Copper Bare Bright declined by $0.36 per pound, representing a ↓5.54% week-on-week drop. #1 Copper Wire and Tubing also lost $0.36 per pound, down ↓5.63% from the previous week. Among the major copper grades, #2 Copper Wire and Tubing registered the sharpest weekly decline, falling ↓5.71%.
USA Midwest Copper Scrap Prices
Copper scrap values weakened further on the Scrap Monster Price Index during the week ending Thursday, November 5, 2026. #1 Copper Bare Bright dropped by $0.36 per pound, marking a ↓5.61% decline from the previous week. #1 Copper Wire & Tubing also shed $0.36 per pound, translating to a ↓5.70% week-on-week decrease. Among the leading copper grades, #2 Copper Wire and Tubing posted the largest percentage loss, falling ↓5.79% over the week to close at a lower level.
USA West Coast Copper Scrap Prices
Copper scrap prices on the U.S. West Coast remained under pressure during the week ending November 5, 2026, according to the Scrap Monster Price Index. #1 Copper Bare Bright declined by $0.36 per pound, representing a ↓5.45% week-on-week drop. #1 Copper Wire & Tubing also lost $0.36 per pound, down ↓5.54% from the previous week. Meanwhile, #2 Copper Wire and Tubing edged lower, recording a ↓5.63% weekly decline.
International Comparison
China Copper Scrap Prices
- All leading copper scrap categories posted modest declines on the Scrap Monster Price Index.
- The steepest declines during the week were recorded by #1 Insulated Copper Wire 85% Recovery, which fell ↓1.43%. #2 Copper Wire and Tubing and #1 Copper Wire and Tubing followed closely, posting week-on-week declines of ↓1.40% and ↓1.39%, respectively.
India Copper Scrap Prices
- All copper scrap categories recorded a week-over-week dip on the Scrap Monster Price Index.
- The commodity to report the biggest fall in prices was Copper sheet cutting, whose prices were down by INR 25,000 per Ton(↓2.64%).
ALUMINUM SCRAP PRICES
- LME Aluminum 3-month closing price, November 5, 2026: $3,064.00 per metric tonne (LME Closing Prices, not Official Prices).
Market Highlights
North America Aluminum Scrap Prices: Aluminum scrap prices weakened during the week under review, with most major grades registering notable losses on the Scrap Monster Price Index. 6063 Extrusions and Old Cast retreated by $0.01 per pound each. UBC prices also moved lower, declining $0.01 per pound, equivalent to a ↓1.14% decrease from the previous week's level. E.C. Aluminum Wire held steady during the week.
Historical Price Charts
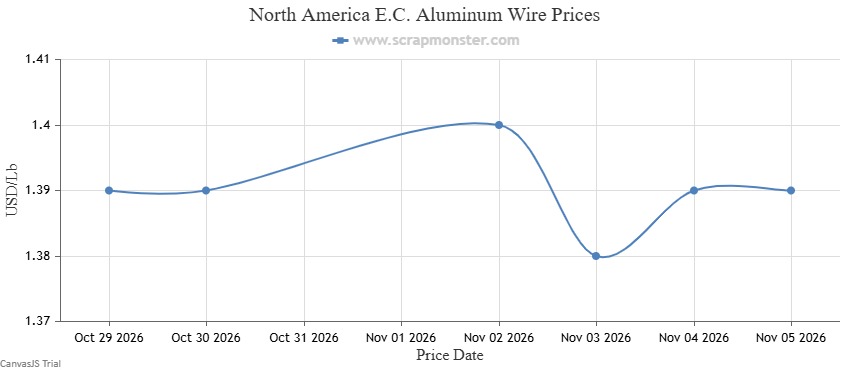
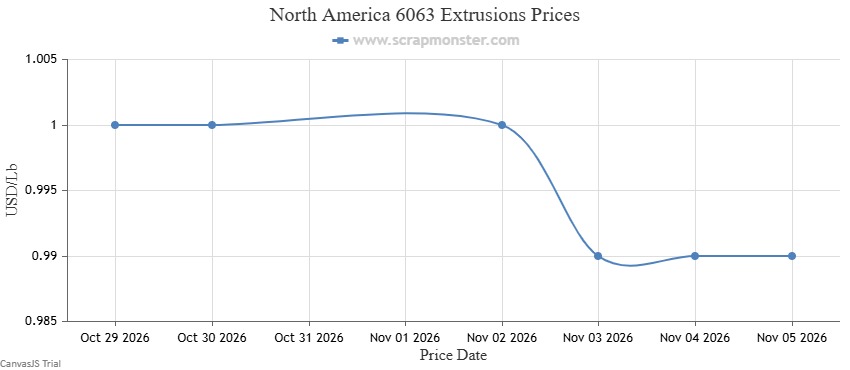
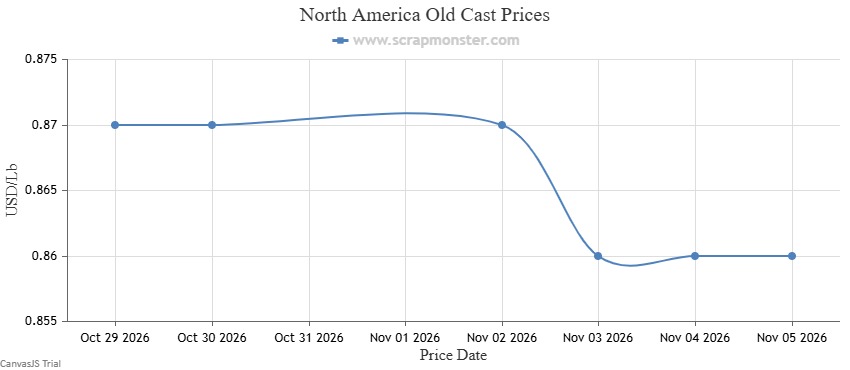
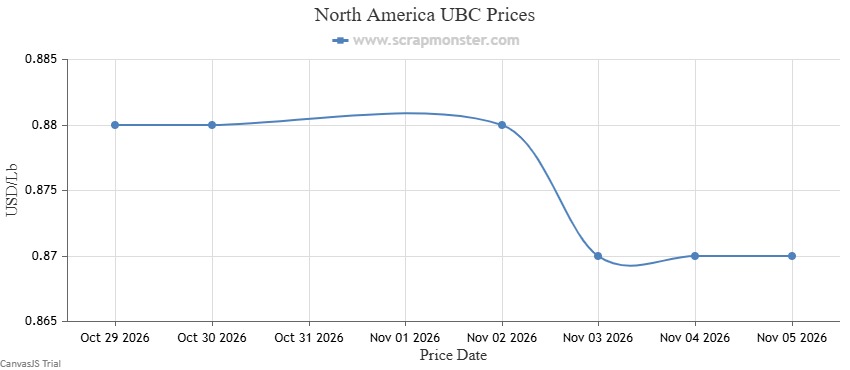
The table below provides weekly price fluctuations in E.C. Aluminum Wire, 6063 Extrusions, Old Cast and UBC.
Category | Weekly change (USD; source units) | % Change |
0 | Nil | |
| -0.01 | -1.00% | |
| -0.01 | -1.15% | |
| -0.01 | -1.14% |
USA East Coast Aluminum Scrap Prices
The aluminum scrap market reported trend reversal during the week, with widespread price declines across major grades. Benchmark grades, including 6063 Extrusions, Old Cast, and UBC, posted declines, reflecting continued weak demand and subdued market sentiment. Meanwhile, E.C. Aluminum Wire prices remained unchanged on the Index.
USA Midwest Aluminum Scrap Prices
Aluminum scrap prices weakened across the board during the past week, with several benchmark grades recording notable losses. 6063 Extrusions posted a $0.01 per pound decrease, equivalent to a ↓1.00% drop. Old Cast also retreated by $0.01 per pound on a week-on-week basis, while UBC prices slipped by the same amount over the period. In contrast, E.C. Aluminum Wire prices reported no variation week-on-week.
USA West Coast Aluminum Scrap Prices
Aluminum scrap prices remained under pressure on the Scrap Monster Price Index during the week ending November 5, 2026. 6063 Extrusions weakened, shedding $0.01 per pound. Old Cast prices declined by $0.01 per pound, representing a ↓1.14% week-on-week decrease, while UBC prices also slipped by $0.01 per pound over the same period, reflecting the broader downward trend in the aluminum scrap market. E.C. Aluminum Wire prices were flat on the Index.
International Comparison
China Aluminum Scrap Prices
- All aluminum scrap categories recorded a modest decline from the previous week's prices on the Scrap Monster Price Index.
- 6063 Extrusions, Old Cast and Old Sheet posted the biggest dips, each falling by CNY 100 per MT (↓0.47%) each.
India Aluminum Scrap Prices
- All aluminum scrap categories recorded a dip on the Scrap Monster Price Index.
- Aluminum utensil scrap and aluminum ingot prices moved lower during the week, with both categories recording an identical decline of INR 2,000 per ton compared with the previous reporting period.
- On a week-on-week basis, Aluminum utensil scrap registered the sharpest decline among the tracked grades, dropping ↓0.62%.
BRASS/BRONZE SCRAP PRICES
Market Highlights
North America Brass/Bronze Scrap Prices: Brass and bronze scrap prices edged lower over the past week, reflecting softness in the market. Yellow Brass declined by $0.09 per pound, marking a ↓2.49% week-on-week decrease. Red Brass also moved lower, losing $0.09 per pound during the same period to finish the week at a weaker level.
Historical Price Charts
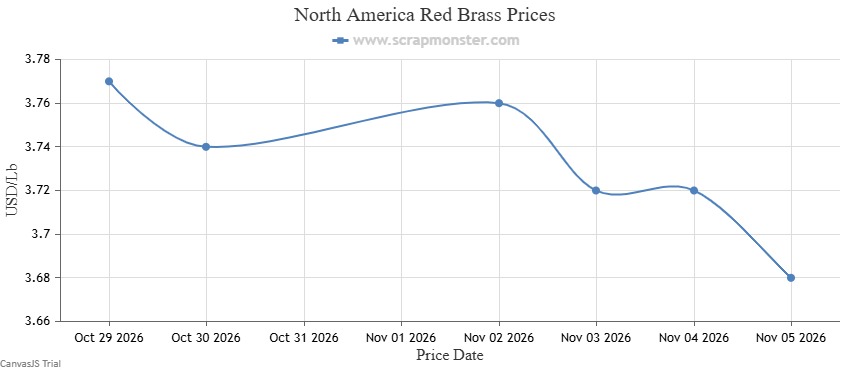
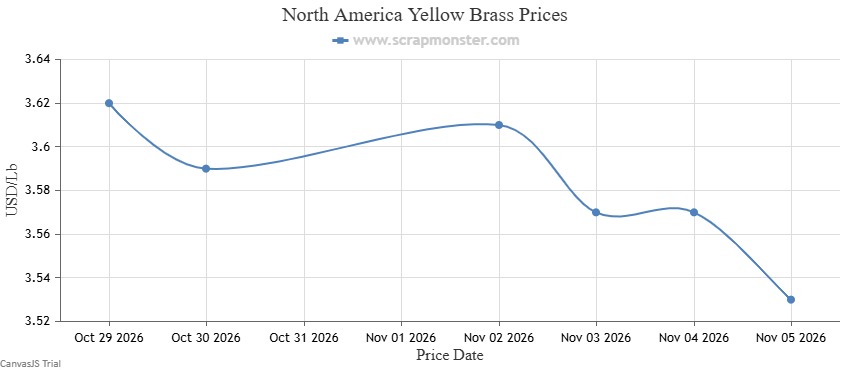
The table below provides weekly price fluctuations in Yellow Brass and Red Brass.
Category | Weekly change (USD; source units) | % Change |
| -0.09 | -2.39% | |
| -0.09 | -2.49% |
USA East Coast Brass/Bronze Scrap Prices
On the Scrap Monster Price Index, Red Brass prices dropped by $0.09 per Lb as of Thursday, November 5, 2026. Yellow Brass also posted a dip in prices, falling by $0.09 per Lb on the Index.
USA Midwest Brass/Bronze Scrap Prices
By the end of the week that ended November 5, 2026, Red Brass prices had dipped by $0.09 per Lb compared to the start of the week. Yellow Brass also recorded a week-on-week decline, edging lower by $0.09 per Lb (↓2.55%).
USA West Coast Brass/Bronze Scrap Prices
Red Brass prices dipped by $0.09 per pound, marking a ↓2.29% decline from the previous week. Also, Yellow Brass prices moved lower, recording a dip of approximately $0.09 per pound on the Scrap Monster Price Index by week’s end.
International Comparison
China Brass/Bronze Scrap Prices
- All brass/bronze scrap categories recorded slight decline on the Scrap Monster Price Index.
- Both Red Brass and Yellow Brass prices were down by CNY 200 per MT.
India Brass/Bronze Scrap Prices
- All brass/bronze scrap categories recorded week-over-week dip on the Scrap Monster Price Index.
- Top Loser: Brass Cuttings, which was down by INR 5,000 per Ton (↓1.17%)
LEAD SCRAP PRICES
- LME Lead 3-month closing price, November 5, 2026: $1,894.00 per metric tonne (LME Closing Prices, not Official Prices).
Market Highlights
North America Lead Scrap Prices: Lead scrap prices remained unchanged throughout the week, reflecting balanced market conditions and steady supply-demand dynamics. Scrap auto battery prices also showed no movement, ending the week at the same levels as the previous reporting period.
Historical Price Charts
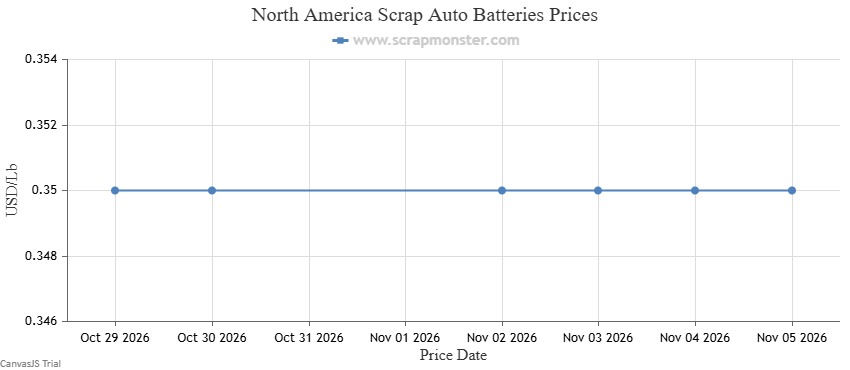
The table below provides weekly price fluctuations in Scrap Auto Batteries.
Category | Weekly change (USD; source units) | % Change |
0 | Nil |
USA East Coast Lead Scrap Prices
The price of Scrap Auto Batteries on the Scrap Monster Price Index held steady as of Thursday, November 5, 2026.
USA Midwest Lead Scrap Prices
Scrap auto battery prices remained stable during the week ending November 5, 2026, with no change recorded compared to the previous week's levels.
USA West Coast Lead Scrap Prices
The prices of Scrap Auto Batteries recorded no change on the Scrap Monster Price Index as of Thursday, November 5, 2026.
International Comparison
China: Auto Battery unchanged; Soft Lead and #2 Lead down CNY 50/MT | India: reported lead categories unchanged.
China Lead Scrap Prices
- Auto Battery prices recorded no variation from the prior week's prices.
- Soft Lead and #2 Lead scrap prices posted a marginal week-on-week decline of CNY 50 per MT each on the Scrap Monster Price Index.
India Lead Scrap Prices
- The prices of all lead scrap categories in the region remained unchanged over the previous week on the Scrap Monster Price Index.
ZINC SCRAP PRICES
- LME Zinc 3-month closing price, November 5, 2026: $3,793.00 per metric tonne (LME Closing Prices, not Official Prices).
Market Highlights
North America Zinc Scrap Prices: Zinc scrap prices weakened during the week under review. New Zinc Die Cast prices slipped by $0.01 per pound, or ↓1.05%, from the previous week, while Old Zinc Die Cast also declined by $0.01 per pound, or ↓1.14%, on the Scrap Monster Price Index.
Historical Price Charts
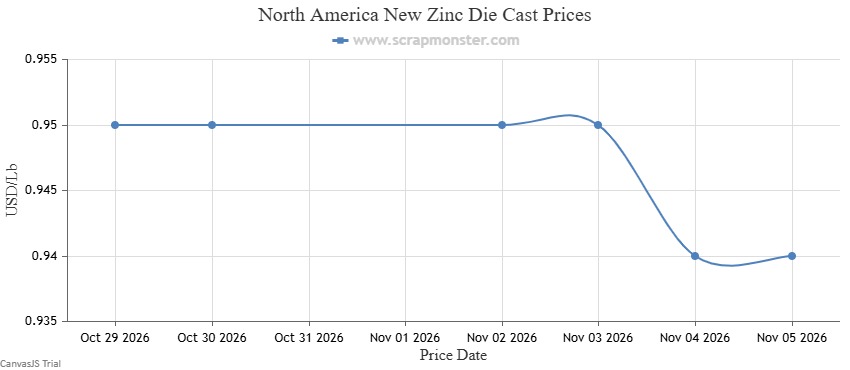
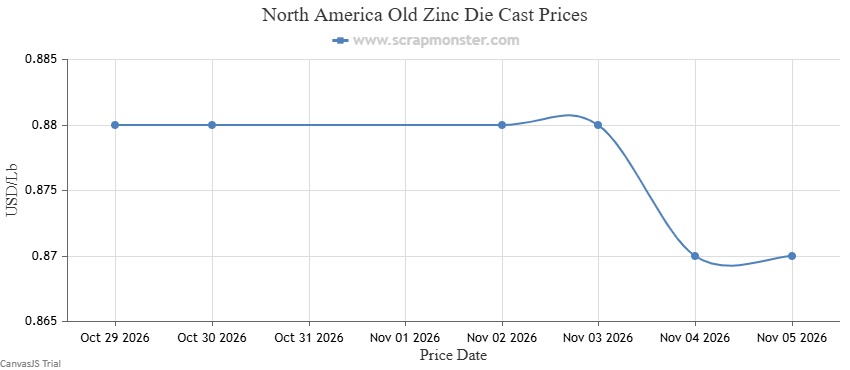
The table below provides weekly price fluctuations in New Zinc Die Cast and Old Zinc Die Cast.
Category | Weekly change (USD; source units) | % Change |
| -0.01 | -1.05% | |
| -0.01 | -1.14% |
USA East Coast Zinc Scrap Prices
The price of New Zinc Die Cast on the Scrap Monster Price Index recorded a decline of ↓1.05% as of Thursday, November 5, 2026. Old Zinc Die Cast also moved lower, falling ↓1.14% from the previous week.
USA Midwest Zinc Scrap Prices
The zinc scrap market moved lower during the week ending November 5, 2026. New Zinc Die Cast declined by ↓1.05% week over week, while Old Zinc Die Cast also slipped by ↓1.14% on the Scrap Monster Price Index.
USA West Coast Zinc Scrap Prices
Zinc scrap prices weakened on the Scrap Monster Price Index during the week ended November 5, 2026. New Zinc Die Cast prices fell ↓1.05% from their prior week’s levels, while Old Zinc Die Cast prices declined ↓1.14% over the same period.
International Comparison
- Shred zinc scrap prices recorded a decline of CNY 100 per MT on the Scrap Monster Price Index. The commodity's price was down by ↓0.56% from the previous week's price during the week ended November 5, 2026.
- Zinc slab prices witnessed a decline of ↓5.23% over the previous week
FERROUS SCRAP
Market Drivers
Turkey – Replacement Buying Supports Import Scrap Prices
Turkish steel mills returned to the import market to secure replacement cargoes for November and December requirements. However, weak rebar demand continued to limit purchasing enthusiasm, suggesting that the recent price recovery was primarily driven by restocking needs rather than a broad improvement in steel consumption.
United States – November Scrap Price Increases
US domestic ferrous scrap prices settled $20–30 per gross ton higher in some markets, while negotiations remained ongoing in others. Strong mill demand and expectations of tighter scrap availability during the winter months supported the upward price movement.
Europe – Weak Mill Demand and Delivery Disruptions
European ferrous scrap markets remained under pressure, particularly in Italy, where prices declined by €10–15 per tonne during the final two weeks of October. Reduced electric arc furnace production, difficulties delivering material to steel mills and anticipated holiday shutdowns weighed on market sentiment.
China – Oversupply and Weak Steel Consumption
Chinese domestic scrap prices softened amid excess material availability and weak demand from steel producers. Elevated finished steel inventories and limited downstream consumption continued to discourage aggressive procurement, putting pressure on domestic ferrous scrap prices.
South Asia – Import Demand Remains Cautious
Pakistan and India continued to experience subdued import scrap trading as mills resisted higher supplier offers. Weak finished steel demand, financing constraints and falling domestic scrap prices encouraged buyers to prioritise local procurement and immediate requirements over imported cargoes.
Finished Steel Demand and Mill Profitability – Key Market Constraints
Weak rebar sales in Turkey and subdued steel consumption across several Asian and European markets continued to constrain scrap purchasing. Mills remained focused on protecting margins, controlling inventories and avoiding expensive raw material purchases without corresponding improvements in finished steel sales.
Overall Market Assessment: The global ferrous scrap market showed mixed trends during the previous week. US domestic prices strengthened, Turkish import prices received support from replacement buying, while European and Chinese markets remained under pressure from weak steel demand, oversupply and operational constraints. South Asian buyers continued to exercise caution, keeping international trading activity selective.
STEEL SCRAP PRICES
Market Highlights
The closing price of various LME 2-month steel contracts on the London Metal Exchange as of November 5, 2026 is provided below:
Steel Scrap CFR Turkey (Platts) - $411.00 per tonne
Steel Rebar FOB Turkey (Platts) - $617.50 per tonne
Steel Scrap CFR India (Platts) - $390.00 per tonne
North America Steel Scrap Prices: Steel scrap prices mostly edged higher, with a few categories holding steady week-on-week. #1 Busheling held firm at prior-week levels, while Shredded Auto Scrap prices increased $15 per ton, or ↑3.53%. HMS 80/20 prices were up by ↑3.33%, while #1 HMS witnessed a sharper increase, surging ↑4.17%.
According to the American Iron and Steel Institute (AISI), U.S. raw steel production totalled 2.053 million NT during the week ended October 31, 2026. This is significantly higher by ↑15.70% week-on-week and ↑19.20% year-on-year.
The capability utilization rate stood at 88.9% (compared to 76.8% in the week ending October 24, 2026).
Region-wise production - Northeast-141,000 NT, Great Lakes-518,000 NT, Midwest-328,000 NT, Southern-1,001,000 NT, Western-65,000 NT
Historical Price Charts
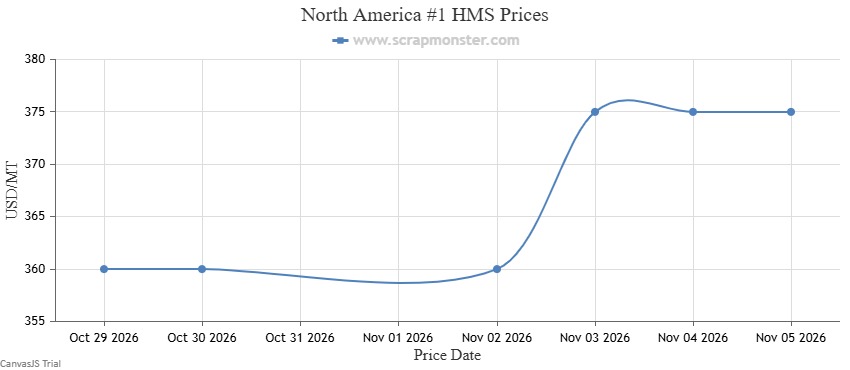
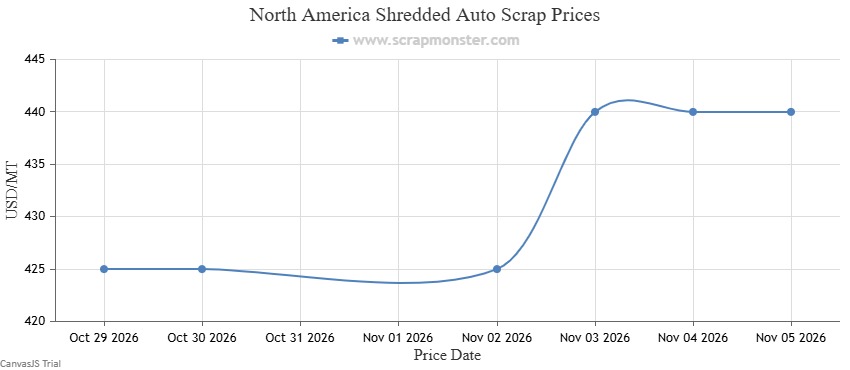
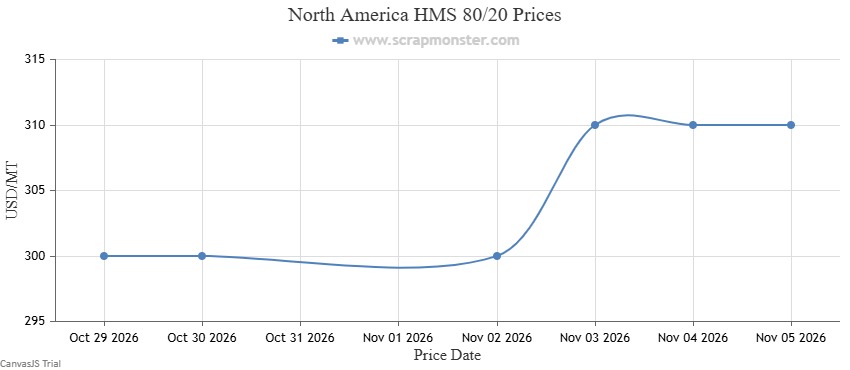
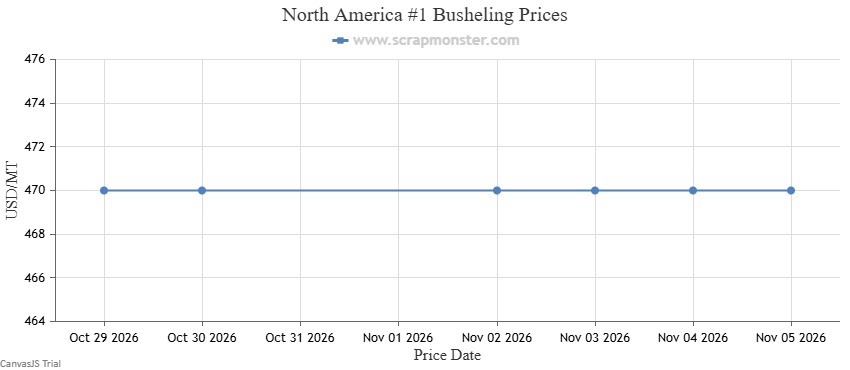
The table below provides weekly price variations in #1 HMS, Shredded Auto Scrap, HMS 80/20, and #1 Busheling.
Category | Weekly change (USD; source units) | % Change |
| +15 | +4.17% | |
| +15 | +3.53% | |
| +10 | +3.33% | |
0 | Nil |
USA East Coast Steel Scrap Prices
Ferrous scrap prices, except for a few listed grades, edged higher during the week ended November 5, 2026, according to the Scrap Monster Price Index, reflecting renewed market momentum. #1 Busheling prices were flat on the Index. However, all other major benchmark grades, including Shredded Auto Scrap, HMS 80/20, and #1 HMS, moved higher from the previous week's level.
USA Midwest Steel Scrap Prices
#1 Busheling prices held steady on the Scrap Monster Price Index during the week. Meanwhile, Shredded Auto Scrap, HMS 80/20, and #1 HMS all posted week-on-week gains, reflecting firmer pricing across several key ferrous scrap grades.
USA West Coast Steel Scrap Prices
Ferrous scrap prices displayed a generally firmer trend during the week ending November 5, 2026, with most benchmark grades advancing on the Scrap Monster Price Index. #1 Busheling remained unchanged throughout the reporting period, while Shredded Auto Scrap, HMS 80/20, and #1 HMS all recorded modest week-on-week gains, indicating improved pricing across the broader ferrous scrap market.
International Comparison
China Flat
China Steel Scrap Prices
- All the steel scrap categories held steady on the Scrap Monster Price Index.
- #1 HMS and Cast Iron Scrap prices remained flat upon comparison with the previous week's prices.
STAINLESS STEEL SCRAP PRICES
Market Highlights
North America Stainless Steel Scrap Prices: The stainless steel scrap market traded downwards over the previous week, with prices edging lower across key grades. 304 SS Solid scrap prices were down by ↓1.49% from the prior week's level on the Scrap Monster Price Index.
Historical Price Charts
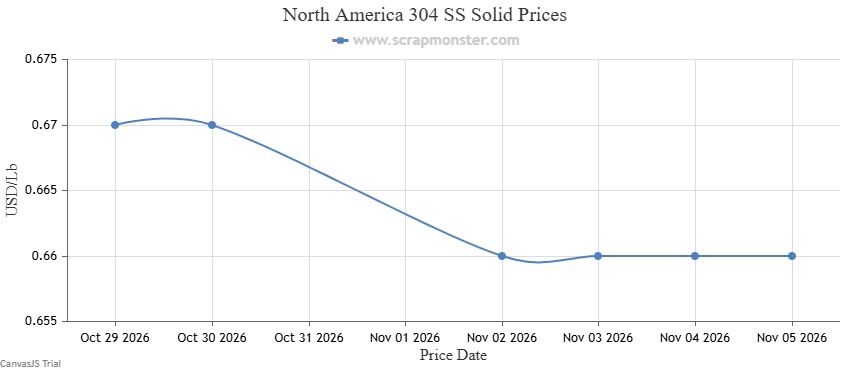
The table below provides weekly price fluctuations in 304 SS Solid scrap.
Category | Weekly change (USD; source units) | % Change |
| -0.01 | -1.49% |
USA East Coast Stainless Steel Scrap Prices
The price of 304 SS Solid on the Scrap Monster Price Index recorded a decline of ↓1.49% as of Thursday, November 5, 2026.
USA Midwest Stainless Steel Scrap Prices
304 SS Solid prices registered a dip of ↓1.49% on the Scrap Monster Price Index. The price of the commodity fell by $0.01 per Lb during the week.
USA West Coast Stainless Steel Scrap Prices
According to the Scrap Monster Price Index, the price of 304 SS Solid dropped by ↓1.49% during the week ended November 5, 2026, recording a week-on-week dip of $0.01 per Lb.
International Comparison
China ↑1.78%
China Stainless Steel Scrap Prices
- All stainless steel scrap categories recorded jumps on the Scrap Monster Price Index.
- Top Gainers: 201 SS ↑2.46%, 304 SS Turning ↑1.94%
Weekly Market Drivers
- U.S. Steel Production- U.S. Steel Output Jumps 19.2%, Utilization Hits 88.9%
- Steel Price- Iowa Manufacturers Face Steel Prices Near $1,400/Ton
- DRI Output- Nippon Steel Produces 1,000 Tonnes of Hydrogen DRI from Lower-Grade Ore
- Investment- U.S. Steel Breaks Ground on $1.9B Arkansas DRI Plant
- Mill shipments- U.S. Steel Shipments Fall 2.1% in September, Up 4.8% YTD
- Iowa Steel Mill- Lee County to Discuss $15B Mesabi Steel Plant November 4
- Quarterly Earnings- ArcelorMittal Posts $391 Million Loss After Ukrainian Steel Plant Shutdown
Global Comparison & Policy Impact
USA vs. China/India
The following regional comparisons reproduce the report’s selected index/grade movements. Percentages may refer to different grades and should not be interpreted as a like-for-like benchmark spread.
- Brass/Bronze: U.S.- ↓2.44%; China ↓0.48% | India ↓1.07%
- Zinc: U.S.- ↓1.10%; China - ↓0.56% | India ↓2.62%
- Steel: U.S.- ↑2.76%; China - Flat
- Stainless Steel: U.S.- ↓1.49% ; China ↑1.78%
Expert Quote:
"There has been an upsurge in Turkish deep-sea scrap buying over the last week for December shipment. Prices paid increased but not as much as the trade expected." — Stephen Miller – Scrap Market Consultant and Steel Market Update Contributor Original Steel Market Update analysis (Nov. 5, 2026)
Market Outlook
Turkey – Moderate Price Support with Limited Upside
Turkish scrap prices are likely to remain relatively firm in the near term, supported by replacement buying requirements, tight US-origin scrap availability and elevated freight costs. However, weak finished steel sales and low mill capacity utilisation could restrict further price increases.
United States – Seasonal Supply Tightness to Support Prices
US domestic scrap prices could receive support from winter-related collection difficulties, reduced material availability and steady mill procurement requirements. However, the sustainability of price increases will depend on steel production rates, mill profitability and export demand.
Europe – Weak Near-Term Sentiment, Gradual Demand Recovery
European scrap prices are likely to remain under pressure in the short term as reduced EAF production, delivery constraints and anticipated holiday shutdowns limit mill purchases. Over the medium term, the commissioning of new electric arc furnaces could strengthen regional scrap consumption and improve demand for high-quality grades.
China – Weak Steel Demand to Restrict Price Recovery
China's ferrous scrap market is likely to face continued pressure from subdued domestic steel consumption, elevated finished steel inventories and competition from exported steel products. Any meaningful price recovery will depend on improved construction-sector demand, stronger mill profitability and increased steel production.
South Asia – Cautious Import Buying to Continue
Indian, Pakistani and Bangladeshi buyers are expected to remain selective in their import purchases, prioritising immediate requirements over inventory accumulation. Weak finished steel demand, financing constraints and relatively competitive domestic scrap availability could limit the potential for significant increases in imported scrap prices.
Electric Arc Furnace Expansion – Medium-Term Demand Support
The expansion of EAF-based steelmaking capacity, particularly in Europe, is expected to provide structural support for ferrous scrap consumption. Up to 20 planned EAF projects could add approximately 34–44 million tonnes of annual steelmaking capacity during 2026–2030, although actual commissioning and utilisation will determine the resulting scrap demand.
Overall Market Outlook
The global ferrous scrap market is expected to remain mixed but relatively stable in the near term, with regional price movements largely dependent on steel mill procurement requirements and scrap availability. Turkey and the US may receive support from tighter supply and seasonal restocking, while Europe and Asia could continue facing demand-related constraints.
Over the medium term, the expansion of EAF steelmaking, evolving trade policies and seasonal supply adjustments could provide additional support to scrap consumption. Nevertheless, weak finished steel demand, excess steelmaking capacity and uncertain global economic conditions are likely to limit the potential for a sustained, broad-based price rally.
WATCHLIST FOR UPCOMING WEEK
U.S
- Tuesday, November 10: U.S. Consumer Price Index (CPI) for October, 8:30 a.m. ET (BLS).
- Thursday, November 12: U.S. Initial Jobless Claims (weekly update).
- Friday, November 13: U.S. Producer Price Index (PPI) for October, 8:30 a.m. ET (BLS).
Europe (EU & UK)
- Thu: United Kingdom Q3 GDP (Preliminary) and September Monthly GDP
- Fri: Eurozone Q3 GDP (Second Estimate) and Employment Change Figures
Asia & Oceania
- Mon: China Consumer Price Index (CPI) and Producer Price Index (PPI), Japan Current Account and Leading Indicators (September)
Benchmark Sources & Methodology
LME three-month quotations refer to the November 5, 2026 LME Closing Prices, not the earlier Official Price fix. COMEX HGZ6 copper futures are an exchange-specific contract. Public ScrapMonster price data in this report are shown as week-over-week changes; regional and international percentages refer to their individually stated grades. LME Closing Prices · CME copper futures history · BLS November release calendar · Steel Market Update / Stephen Miller ·